Chapter 9 - THE PENSION LETTERS
Three years after Leonard Shaw’s conviction, Alder Crest sent every pension participant a plain-language letter explaining that the plan had returned to full funding under independent actuarial review.
Rachel read the draft before distribution.
No corporate self-congratulation.
It acknowledged past misstatements.
Recoveries.
Company contributions.
New controls.
She approved.
Then letters came back.
Retirees wrote.
Some angry.
“Why should we trust you now?”
Fair.
The pension committee hosted virtual forums with independent fiduciaries, not only executives.
Rachel attended.
One retired machinist named Samuel Brooks asked:
“Did anybody lose a pension check?”
No.
Payments continued.
“But could we have?”
Potentially risk increased, but federal protections/plan assets complicated. Rachel answered carefully:
“The fraud put the plan in a weaker position than employees were told. That was unacceptable. The remediation is designed to restore the funding and oversight.”
No exaggeration.
Another asked why board not jailed.
Because negligence not same as criminal intent.
Hard answer.
Accountability different.
Eleanor Price joined one forum after stepping down.
She apologized directly.
No legal requirement.
That mattered.
Charles Hale wrote separately to retirees.
He offered restitution funds from tainted distributions.
No hero.
He acknowledged founder culture.
His letter said:
“My name became an authorization code long after I stopped holding authority. That should never happen again.”
Powerful.
Alder Crest removed founder-family language from internal approvals.
No “Hale family office.”
Only legal entities and named authorized persons.
Specific.
Rachel helped.
Pension recovery became company’s moral test.
Would shareholders accept lower buybacks to fund obligations?
Board voted yes.
Some investors complained.
Company explained fiduciary.
No need rank.
Over time, credibility recovered.
Rachel was promoted to CFO after Vanessa? Not too soon. Three years maybe eventually after Maya's initial CFO from outside. Let's say five years after scandal, when new CFO retired, Rachel entered search.
She almost declined.
The title.
Then applied.
External search.
Board chose her.
Why?
Experience, treasury leadership, controls, not heroism.
She negotiated conditions.
Direct audit committee access.
No compensation metric tied solely to adjusted earnings.
Independent pension committee.
Strong.
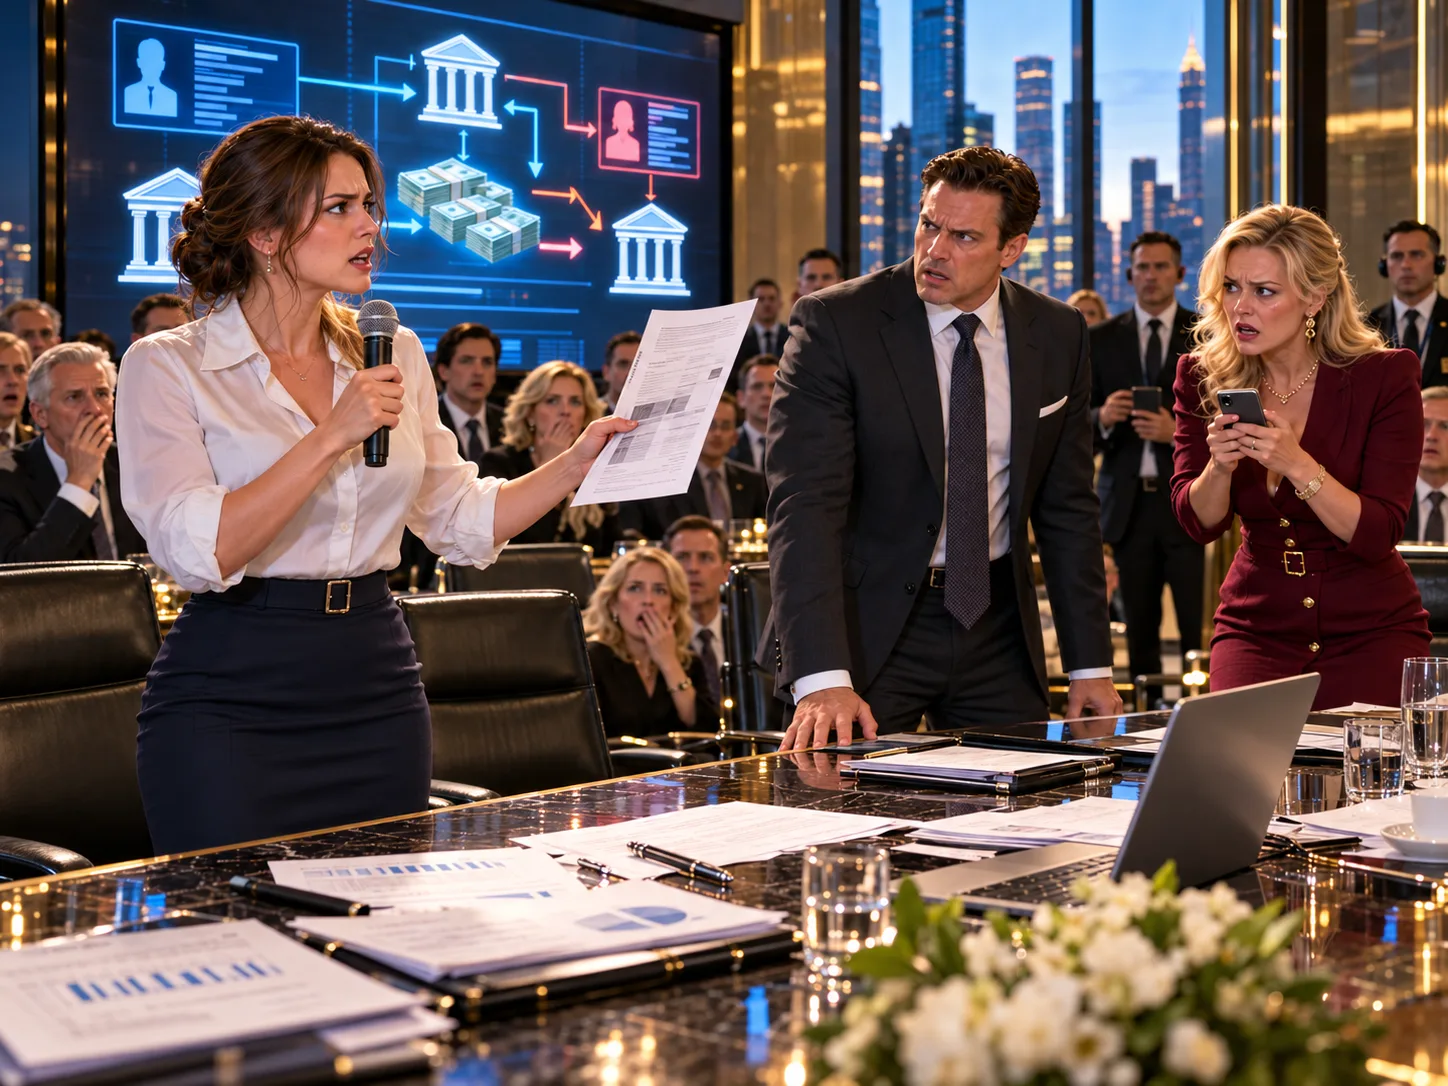
Her first shareholder meeting as CFO occurred in same hall.
She stood where Vanessa once threatened handcuffs.
Rachel felt weight.
She began:
“Before financial results, I want to review pension funding.”
Transparency.
No hiding at end.
Shareholders listened.
At Q&A, one investor asked:
“Are controls now too restrictive for growth?”
Rachel answered:
“Controls should make authorized risk easier to distinguish from unauthorized risk. If they only slow everything, we designed them badly.”
Good.
Balanced.
The company grew.
Made acquisitions.
No fear of reserves.
Rachel authorized large transfers routinely but never alone.
Dual controls.
She welcomed.
Power constrained.
She had lived alternative.
Her personal finances remained ordinary.
People assumed scandal made her rich through lawsuit.
She did settle civil claims against Grant/company for assault and wrongful accusation? Could be. Alder Crest compensated under settlement, no details. She used part for home and donated part to employee legal-defense fund? Could but don't martyr. Let's say she received settlement and kept/invested mostly, plus funded small scholarship.
She had no shame.
Damages for harm.
She invested.
Took a month trip to New Zealand.
Enjoyed.
No need give all away.
She established scholarship for first-generation accounting students later because wanted, not guilt.
Rachel’s mother teased:
“Twenty million disappeared and you finally took vacation.”
Rachel laughed.
The scandal became less emotionally immediate.
Clips still online.
New employees occasionally recognized.
She disliked.
But no panic.
One day in elevator someone said:
“You’re the woman who exposed twenty million theft.”
Rachel replied:
“More like sixty-eight million pension fraud.”
Finance people correct numbers.
They laughed.
Humor.
Jonah sent message from new job:
Still reconciling?
Always.
Friendship.
Pension letters became symbol of institutional promise finally backed by verified assets.
No fake valuations.
No shell redemption.
Just numbers that reconciled.
Rachel loved that more than headlines.
The pension committee also established a retiree advisory panel, and Rachel initially worried it would become symbolic.
The retirees prevented that.
They asked blunt questions executives avoided.
Why pay active-management fees?
Why invest private markets?
Why were reports so technical?
Rachel loved.
They simplified quarterly summaries.
Funding ratio.
Contributions.
Major risks.
Fees.
Independent auditor status.
No glossy.
One retired engineer said:
“If you need twelve pages to explain why money exists, maybe check whether it exists.”
Everyone laughed.
That sentence went on Rachel’s whiteboard temporarily.
Communication control.
Fraud hides in complexity.
But oversimplification can mislead.
Balance.
The panel did not vote investments but could escalate.
Their presence improved accountability.
Rachel also supported automatic data sharing from custodian to audit committee.
No executive filtering.
Again.
Pension letters became less legalistic.
Trust is partly comprehension.
People cannot challenge what they cannot parse.
Rachel saw same with shareholders.
At first scandal, Grant weaponized complexity.
He accused her with simple story:
Employee stole twenty million.
Simple lies beat complex truth temporarily.
Rachel’s screen made truth simple enough:
Money went to Grant.
Then Vanessa.
Later story became complex again.
Communication challenge.
She learned to explain without distortion.
This skill helped as CFO.
A good executive should make complexity understandable, not use it as shield.
Her mother Linda never understood pension derivatives but understood:
“Don’t let boss move retirement money into his own company.”
Rachel said:
“Pretty much.”
Sometimes plain language is enough.
When the pension finally reached full funding, some executives proposed a celebratory campaign.
Rachel opposed.
“Employees did not ask us to rescue them from a problem we created.”
The board agreed.
No victory banners.
The letter simply stated facts.
Contribution amount.
Recovery amount.
Funding status.
Independent verification.
The absence of self-congratulation improved trust more than marketing would.
Retirees still remembered.
They did not need company pretending hero.
Rachel personally met Jonah at a coffee shop after the announcement.
He had left Alder Crest but still received updates.
“You did it,” he said.
“We did it,” she corrected automatically.
He rolled his eyes.
“Fine. Thousands of accountants did it.”
They laughed.
Then Jonah became serious.
“I almost didn’t send that package.”
“Why?”
“I thought maybe I misunderstood.”
Rachel nodded.
That is how fraud survives.
People assume someone more senior knows.
She told him:
“Next time, verify and escalate. Don’t wait for certainty you can’t possibly have.”
He smiled.
“Very CFO.”
She groaned.
The conversation reminded Rachel that whistleblowing often begins with doubt, not certainty.
Systems should allow questions before someone has a complete case.
Alder Crest’s new program did.
Reports could say:
I don’t understand this.
Not only:
I have proof of fraud.
That lowered barrier.
One early report exposed no misconduct but fixed a broken vendor approval process.
Another identified duplicate payment.
Small savings.
Culture.
Rachel saw this as pension scandal’s most valuable legacy.
May you like
Not fear.
Permission to ask.