Chapter 5 - THE BOARD THAT DIDN’T ASK
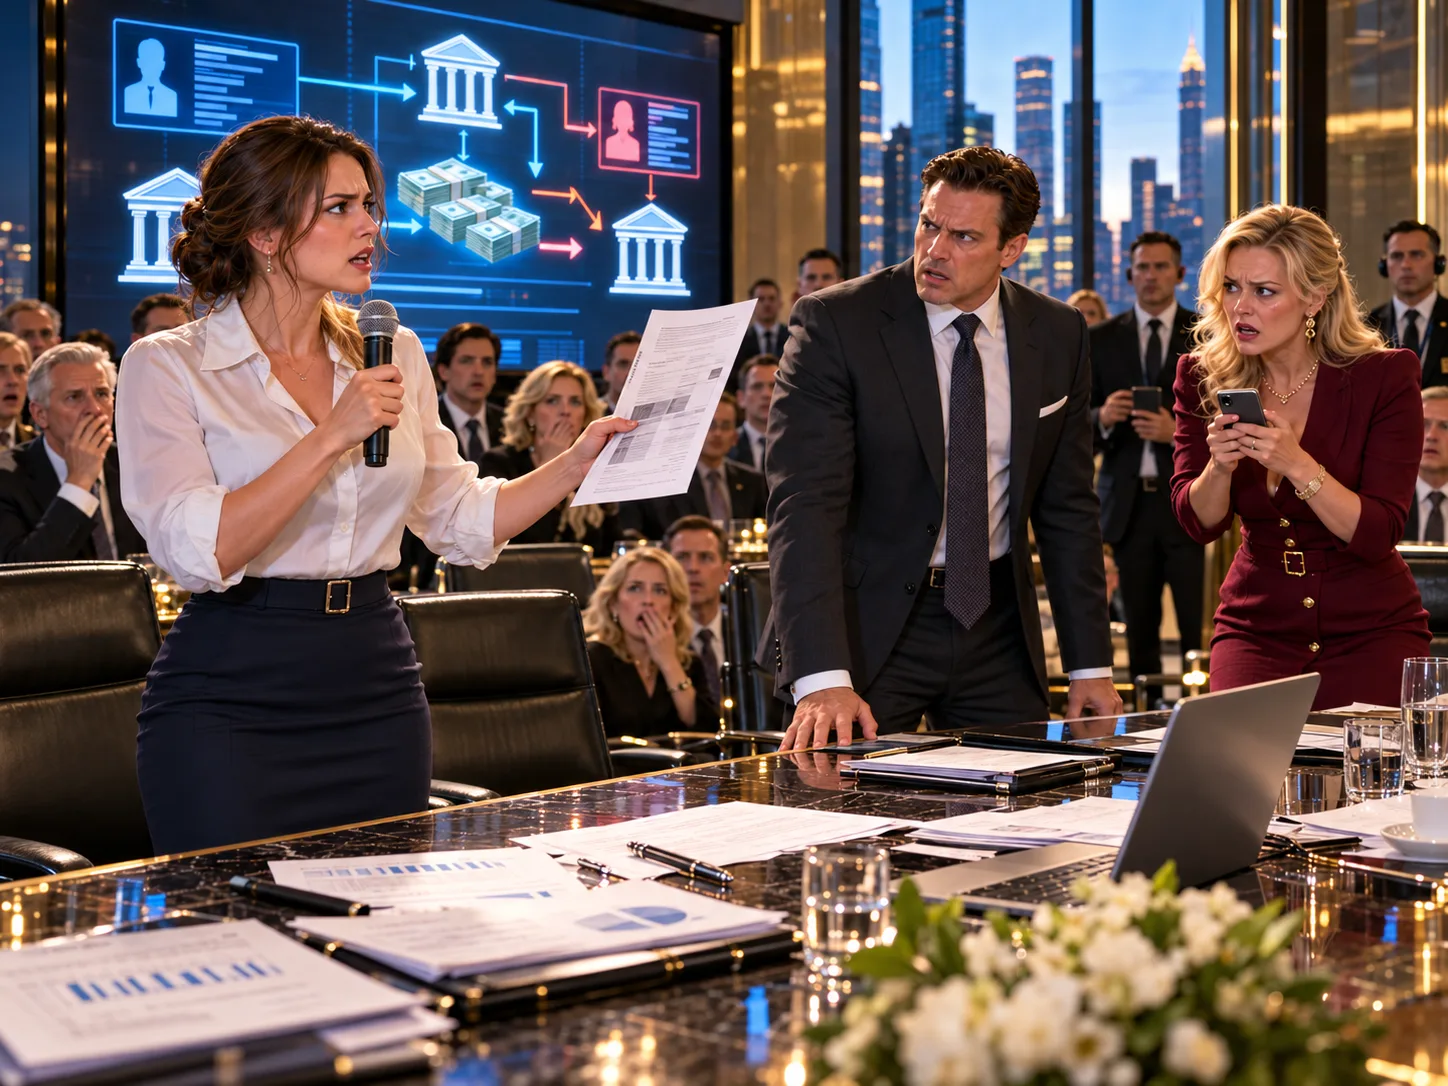
Alder Crest’s independent investigation eventually produced a six-hundred-page report, but Rachel believed the most important sentence was buried near the middle: the fraud persisted because senior leadership converted trust into an exemption from verification.
The board had received warning signs.
Not proof.
Warnings.
Pension committee minutes noted valuation delays.
Outside auditor requested independent confirmations twice.
Vanessa supplied letters from funds through Cedar Lane.
Accepted.
Grant pushed acquisition targets despite reserve pressure.
Accepted.
Leonard Shaw attended private dinners with directors and described alternative investments as “founder-approved strategy.”
Accepted.
Charles had approved nothing.
No one called.
Why?
Charles retired.
People assumed Leonard spoke for him.
Family name substituted.
Jonah Reed’s supervisor dismissed discrepancies because “CFO already reviewed.”
Mark told Rachel actuarial adjustment.
Hierarchy substituted.
The report did not accuse board of intentional fraud.
It criticized oversight.
Eleanor Price, board chair, faced question whether resign.
She offered.
Independent directors asked her remain six months for transition then step down.
She agreed.
No ego.
She publicly said:
“I was not part of the theft. I was part of a system that did not challenge the people who were.”
Strong.
Shareholders appreciated.
Some demanded whole board removed.
Votes later replaced several.
Governance.
Rachel was invited to join special internal-controls committee as employee adviser.
She hesitated.
Would this turn her into company mascot?
She asked terms.
One-year.
No public relations use without consent.
Compensation.
Independent reporting.
She accepted.
Not because loyalty.
Because expertise.
She insisted Jonah join too.
He accepted part-time advisory.
Their first recommendation:
Stop calling whistleblowers “noise.”
Obvious.
They created protected escalation line outside management.
No report routed to implicated supervisors.
Another:
High-value treasury transfers require dual independent confirmation if executive override used.
Another:
Beneficial ownership verification for private counterparties.
Another:
Pension valuation directly confirmed by custodian and underlying manager, not adviser only.
Technical but safe.
The company contributed significant cash to pension fund to restore security, funded through asset sale, insurance recovery, executive clawbacks, and reduced buybacks.
Shareholders absorbed cost.
Employees should not.
This became board principle.
Grant’s compensation clawed back tens millions.
Vanessa’s.
Others.
Leonard assets frozen.
Recovery.
Pension eventually restored near full funding.
Not immediate.
Alder Crest issued transparent restatement.
Stock price fell.
Company survived.
Rachel watched employees panic about jobs.
Management held town halls.
No false reassurance.
Some projects delayed.
Bonuses reduced.
But layoffs minimized.
This mattered.
Fraud costs real.
No happy ending without consequence.
Rachel’s supervisor role? Mark removed. She was offered treasury director.
She declined initially.
“Not while investigation ongoing.”
Good.
Later competed after open process.
Maybe.
Her personal reputation transformed.
Some coworkers who avoided her after accusation apologized.
One said:
“I thought if Grant said it publicly, there had to be evidence.”
Rachel answered:
“That’s the problem.”
Authority influences belief.
She did not punish socially.
But remembered.
HR arranged no retaliation.
Security personnel who stood while Grant grabbed her were reviewed.
One officer said company policy prohibited touching CEO unless physical danger clear.
Training changed.
Rank does not excuse assault.
Grant faced separate assault charge for grabbing/shoving Rachel plus financial crimes.
Rachel filed workers’ compensation? Physical bruise. She had shoulder injury minor.
She did not dramatize.
Medical records.
Therapy.
Public clip replay triggered.
She hated becoming viral.
People praised her for pulling curtain.
Merchandise memes.
She asked company to stop using image.
They had not, good.
Media requests.
She declined most.
One interview eventually about controls, not fight.
She said:
“The important part wasn’t that I grabbed a microphone. It was that transaction records existed and could be verified.”
Good.
No hero myth.
Leonard’s defense began blaming board.
Some merit in oversight, not excuse.
Grant blamed Leonard.
Vanessa blamed Grant and Leonard.
Mark blamed Vanessa.
Sloan blamed data.
Everyone downward/upward.
Rachel saw pattern.
Accountability means own choices.
At plea/trials, evidence would separate.
The board report found Grant had personally approved at least fifteen suspicious transfers.
Vanessa created false certifications.
Mark altered access logs.
Sloan knowingly signed valuations without underlying support after year two.
Leonard orchestrated entities and directed flows.
Clear.
One open question:
Did Charles Hale know any pension assets flowed through family office?
Report found no.
He received quarterly statements from Leonard with aggregate investment returns.
After stroke, Rebecca reviewed but trusted.
Some distributions to legitimate family trust included commingled funds.
Charles offered restitution of tainted portion once traced.
No criminal involvement.
This vindicated founder personally but highlighted governance.
Charles issued statement:
“I trusted Leonard longer than I verified him. That is my failure as a client, not authorization for theft.”
Good.
Rachel met Charles once at board reform session.
He thanked.
She said:
“Jonah found it first.”
Charles thanked Jonah.
No hierarchy.
He also apologized for culture his family created.
Rachel appreciated.
Then he asked:
“Will you stay at Alder Crest?”
She said:
“I haven’t decided.”
He smiled.
“Good answer.”
Choice.
The board chapter reframed company as neither victim only nor villain.
Institution contained fraud and people who stopped it.
Its future depended on learning, not branding scandal as one bad CEO.
Rachel would decide based on evidence of change.
The board report included interviews with dozens of employees who had noticed fragments without seeing pattern.
Accounts payable clerk questioned Cedar Lane invoices.
Told executive-approved.
IT analyst noticed repeated emergency credential resets.
Told CFO project.
Pension operations specialist saw fund confirmations arrive through same adviser instead of independent managers.
Told not her lane.
Each warning isolated.
No one channel assembled.
The new escalation system therefore emphasized cross-functional pattern detection.
Reports tagged by entity, executive, control type.
Independent compliance could connect.
Rachel warned against surveillance culture.
Employees needed privacy.
System should aggregate concerns, not gossip.
Careful.
The company also changed executive expense review.
Grant’s lake property acquisition had been personal, but traces appeared in payments.
No executive could approve own related-party reimbursement.
Boring.
One director asked whether scandal showed family-controlled public companies inherently unsafe.
Rachel refused broad.
“It showed our specific controls failed around family influence.”
Good.
No ideology.
Charles retained shares but voting capped through governance settlement until estate.
This reduced informal.
Rebecca chose sell some over years.
Diversified.
Family wealth no longer tied entirely.
Healthy.
Eleanor Price’s transition off board became model accountability.
She did not commit crime.
She still accepted leadership consequence.
Some praised.
Some said scapegoat.
She herself said:
“Accountability is not identical to guilt.”
Rachel remembered.
This helped in leadership.
When one of Rachel’s team later made costly but honest forecast error, Rachel did not treat as fraud.
They fixed process.
Consequences maybe performance coaching.
No moral collapse.
After living through deliberate deception, she became better at distinguishing mistakes.
This prevented fear culture.
Employees should report because not every irregularity becomes accusation.
The old company had two extremes: executive trust and harsh scapegoating.
New culture aimed middle.
Evidence.
Questions.
May you like
Proportion.
That balance made reforms durable.