Chapter 2 - THE MISSING PENSION MONEY
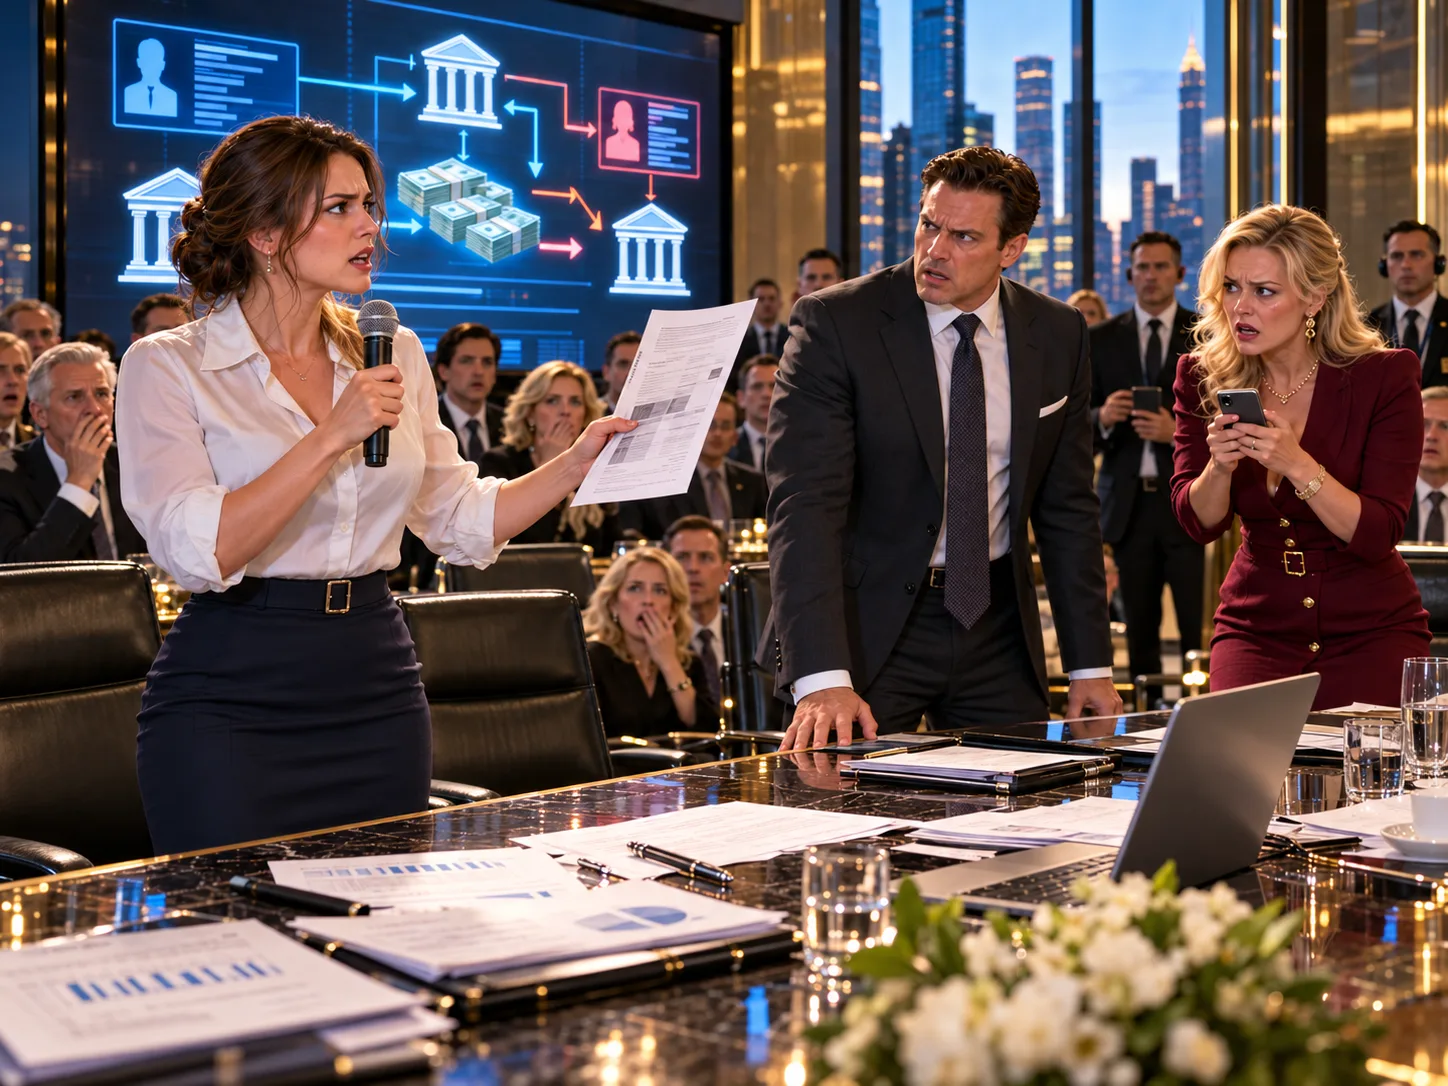
The shareholder meeting ended under federal supervision, and by noon Alder Crest Technologies had suspended both its CEO and CFO while the board formed an emergency independent committee and Rachel Morgan learned that the twenty million dollars she discovered was only the visible movement in a fraud that had begun years earlier.
Special Agent Daniel Ruiz interviewed Rachel in a conference room on the twentieth floor.
Independent board counsel sat in.
No company executive.
Good.
Rachel explained the reconciliation.
The acquisition reserve account.
Meridian Strategic Holdings.
The blocked access.
The confession.
Grant’s physical coercion.
Vanessa’s threat.
Ruiz listened without interrupting.
Then asked:
“When did you first notice irregular pension funding?”
Rachel paused.
“Pension?”
Alder Crest maintained a defined-benefit retirement plan for older employees inherited from two acquisitions.
Rachel’s treasury team funded scheduled contributions.
Actuaries handled liabilities.
She rarely examined investment assets.
Ruiz slid over a report.
For three years, Alder Crest public filings said its pension plan was approximately ninety-two percent funded.
Internal custodial records suggested something closer to seventy-six.
The difference:
About sixty-eight million dollars.
Rachel stared.
“How?”
“Fictitious private investments.”
The pension plan reported holdings in three alternative funds.
North Bridge Infrastructure.
Solstice Credit Opportunities.
Harbor Peak Growth.
On paper, valuable.
In reality, two were shell vehicles.
The third held only a fraction of reported assets.
Someone had been overstating pension value.
The twenty million transfer Rachel saw entered the custodial account days before an external audit confirmation.
It was a temporary patch.
Window dressing.
Money moved from company reserve into Grant’s entity, then Vanessa’s advisory company, then pension custodian.
Why route through private companies instead of direct contribution?
To make it look like proceeds from a legitimate external investment redemption.
Cedar Lane was listed as adviser to one of the pension funds.
Vanessa could fabricate redemption documentation.
Grant’s Meridian entity supplied the cash.
But where would acquisition reserve get restored after audit?
Ruiz suspected another borrowing or asset sale.
Ponzi-like corporate concealment.
Rachel felt sick.
Retirees.
Employees.
Not abstract shareholders.
People’s pensions.
She asked:
“Who started it?”
Ruiz did not answer yet.
Federal investigation began nine months earlier after an anonymous whistleblower sent valuation discrepancies to the Department of Labor and securities regulators.
The whistleblower used internal pension documents.
Agents believed someone inside finance.
Was it Vanessa?
No.
She had reason to conceal.
Grant?
No.
Then who?
Ruiz said:
“We thought it might be you.”
Rachel laughed once.
“Great.”
“Your credentials touched several reconciliation files.”
“They should. It’s my job.”
“Exactly why we did not act.”
They watched.
Then Rachel’s account was used two weeks earlier to open a secure pension folder at 2:13 a.m.
Rachel was asleep.
Her credentials compromised.
Someone had begun framing her before the shareholder meeting.
The confession was only final step.
Who had access to her authentication token?
Her supervisor, treasury director Mark Ellison, could initiate recovery.
Vanessa’s office could authorize.
IT security could reset.
Grant’s executive security administrator could override.
Multiple.
Ruiz asked about Mark.
Rachel trusted him.
That now felt dangerous.
She said:
“He told me not to ask questions about pension settlements last month.”
Ruiz wrote.
“What exactly?”
Rachel remembered.
A scheduled $4.2 million transfer labeled “benefit equalization.”
She asked why treasury paid outside normal calendar.
Mark said actuarial adjustment.
She accepted.
Now likely connected.
Ruiz showed transfer.
Destination North Bridge Infrastructure.
The shell fund.
Money had been leaving company into fake pension investments too.
So the scheme worked both directions.
Alder Crest contributions moved into shell vehicles.
Shell valuations inflated plan assets.
When audits approached, temporary cash moved back as fake investment redemptions.
Money cycled.
Where did profits go?
Private accounts.
Grant.
Vanessa.
Others.
Rachel asked:
“How much was actually stolen?”
“Still calculating.”
Ruiz estimated at least forty-eight million diverted over four years, perhaps more.
The twenty million was emergency cover.
Not original theft.
Rachel closed eyes.
Grant had tried to make her confess to twenty million because he needed someone blamed for visible movement, while deeper pension loss remained hidden.
But why did Grant look shocked when he saw Vanessa’s second transfer?
Ruiz had same question.
He showed recovered messages.
Grant to Vanessa:
Move reserve through Meridian, then send to Luxembourg holding. We replace after acquisition closes.
Vanessa replied:
Understood.
So Grant intended offshore movement, likely to protect stolen money or finance something.
Vanessa instead sent it into Cedar Lane and pension account.
She double-crossed him.
Why?
Maybe to cover pension deficit and protect herself from regulators.
Grant expected twenty million to disappear offshore.
Vanessa used it to patch hole.
Then planned blame Rachel for reserve theft.
Two schemes intersected.
Grant had his own.
Vanessa had survival strategy.
The board chair, Eleanor Price, joined.
She looked devastated.
“We need to know whether the board was lied to.”
Ruiz answered:
“Yes.”
Eleanor flinched.
Pension committee received quarterly reports certified by Vanessa and an outside actuarial consultant named Peter Sloan.
There.
Another participant.
Sloan valuations supported false assets.
His firm had received unusual consulting fees from Cedar Lane.
Ruiz had warrants.
Rachel asked who anonymous whistleblower was.
“Protected.”
Fair.
Then her phone—replacement issued by IT under agent supervision—received a message from unknown number.
Do not trust Mark Ellison.
Attached:
A photograph.
Mark entering Cedar Lane’s office at night three months earlier.
Rachel showed immediately.
Ruiz did not react.
They already knew.
“Who sent this?”
“We’re tracing.”
Mark had been under surveillance.
He was not just supervisor.
He approved fake pension settlement coding.
Maybe he was the internal operator.
Rachel felt betrayed.
Mark hired her.
Mentored.
Recommended promotions.
Had lunch with her mother once at company picnic.
Again, fraud often lives inside trust.
Agents arrested Mark later that afternoon after he attempted to wipe a laptop.
His reaction:
“I was following Vanessa’s orders.”
Maybe.
Digital evidence would decide.
He admitted resetting Rachel’s credentials under instruction from CFO office.
He prepared access logs placing Rachel in pension folder.
Who drafted confession?
Grant’s general counsel? Corporate counsel might be unaware. Investigation traced to Grant’s personal attorney outside company, not board counsel.
Grant and Vanessa had agreed on Rachel as scapegoat despite separate agendas.
That was crucial.
They both needed someone mid-level with legitimate treasury access.
Rachel had just enough authority to plausibly move money, not enough power to defend against executives.
They chose her because she found discrepancy.
If she stayed silent, maybe no frame yet.
Once she asked, she became threat.
The board placed Rachel on paid protective leave, not suspension.
Eleanor apologized.
Rachel said:
“Don’t apologize yet. Preserve everything.”
Good.
She requested whistleblower protections and independent counsel.
No loyalty theater.
Ruiz approved.
Before leaving, he said:
“There’s one more reason we think the pension fraud goes higher than Grant and Vanessa.”
Rachel stared.
“How much higher can it go?”
“The board?”
He shook head.
“The money from North Bridge did not all go to them.”
He showed beneficiary ledger.
A large portion flowed to a private trust in Delaware.
Owner obscured.
But trustee bank records showed distributions to one person.
Alder Crest’s retired founder and former chairman.
Charles Hale.
Grant’s father.
Rachel knew the name.
Everyone did.
Charles Hale had built Alder Crest thirty-two years earlier and stepped down five years ago after a stroke.
He was publicly celebrated as the company’s moral center.
His portrait hung in the lobby.
Rachel looked at Ruiz.
“You think the founder was stealing pension money?”
Ruiz answered carefully.
“We think money reached a trust bearing his name.”
Not same.
Good precision.
Then he added:
“And Charles Hale claims he has never seen the trust before.”
Rachel felt the story shift again.
Someone may have been using the founder’s identity too.
If so, Grant and Vanessa were not merely stealing.
They were building a false trail upward and downward at the same time.
Rachel beneath them.
May you like
Charles above them.
A scapegoat and a shield.