Chapter 5 - DANIEL VOSS
Daniel Voss had represented the Hale family for thirty-two years. He drafted Eleanor’s trust amendments, handled Morgan’s probate transition, and knew the Lake Forest property better than almost anyone alive. That history made his conduct more serious because he did not need to steal access. He already had it.
His first defense was simple: “I was structuring a family transaction.” But Morgan had never engaged him for that transaction. Julian had. Voss accepted Julian as a client while remaining attorney of record for Morgan’s trust-related matters, then accepted a ten-percent equity interest in the borrowing entity.
Professional ethics counsel reconstructed the timeline. In month one Julian asked a general financing question. Month two Voss drafted a conceptual structure. Month three Julian offered future equity in lieu of part of Voss’s fee. Month four Voss accepted through a family trust. Month five Voss contacted Great Lakes Trust and said Morgan was considering a principal-residence election. Month six Julian began the residency dossier. Month seven the tracker was commissioned. Month eight the preliminary lender package circulated. Month nine Morgan discovered the necklace.
At no point did Voss send Morgan a conflict waiver. At no point did he disclose his ownership interest. At no point did he advise Morgan to obtain independent counsel.
Did he authorize illegal tracking? The evidence was nuanced. He knew Julian wanted occupancy data. He warned against undisclosed tracking and told Julian not to use device data in legal filings. But after learning the necklace concealed a tracker without Morgan’s consent, Voss did not withdraw. He wrote: Keep that data out of anything I sign.
Another message was worse. Julian asked: If she asks how we know overnights? Voss replied: Use utilities/deliveries. Not device data. He was insulating documents from the tracker, not protecting Morgan from the tracker.
The preliminary lender memo Voss signed stated that the beneficiary “has established principal occupancy and intends to execute formal election.” Morgan had never told him that. He inferred intent from Julian’s narrative and the occupancy dossier. The bank relied on the statement only preliminarily; no money moved. Still, it was unsupported.
The state bar placed Voss on emergency interim suspension pending proceedings. His firm accepted his resignation. Morgan brought a malpractice claim seeking actual costs: independent counsel, forensic review, trust-administration expenses, and security remediation. She did not claim an $8.6 million loss because she had not lost the house.
Voss eventually surrendered his equity interest in the LLC. Hale Lake Residence Holdings dissolved. The transaction died.
Craig Mills’s role was more direct. Craig owned Lakeview Stewardship Partners and embedded the tracker inside the pendant. He knew consent was questionable. Julian paid $18,000 for the custom work and promised Lakeview a $300,000 property-management contract if the financing closed. Craig’s financial incentive was obvious.
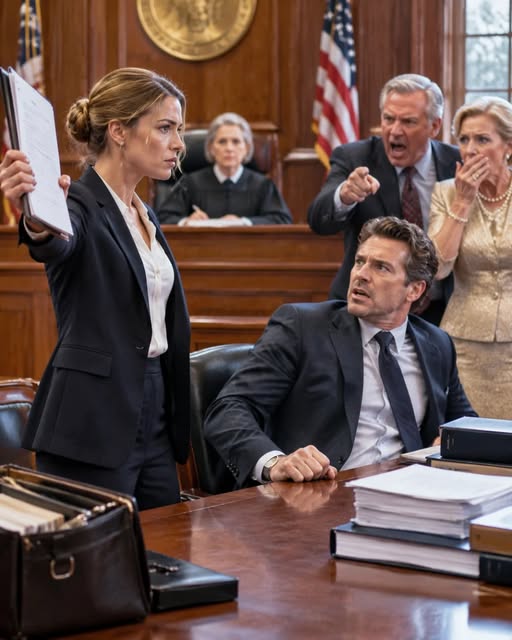
Morgan confronted Voss once in deposition. “Why didn’t you call me?” Voss answered, “I thought Julian was trying to save his company and that once you saw the transaction, you would agree.” Morgan stared at him. “You thought my answer didn’t matter until the end.” Voss said nothing for several seconds, then: “Yes.”
That was the core. Consent had been reduced to a final signature. Everything before it was treated as preparation and therefore permissible. But preparation had already invaded Morgan’s movements, legal files, trust communications, and home.
Great Lakes Trust reviewed its own processes. Why had it begun reviewing the transaction without Morgan’s direct confirmation? Because Voss remained legacy counsel on older records. The trustee had refused final approval without Morgan, which prevented damage, but it updated policy anyway: legacy counsel authority would expire unless beneficiaries periodically reaffirmed it; new secured-borrowing requests would require direct digital confirmation; conflicts would be re-attested.
Morgan created her own rule: no spouse, lawyer, adviser, or family member received trust information without current written consent.
The divorce remained separate. Julian’s lawyers argued Morgan had enjoyed the lifestyle his business created and that not every asset in the marriage belonged to her. That was fair as a marital-property issue. It did not give Julian rights to the Lake Forest trust.
Morgan did not seek to take everything from him. She wanted the marriage ended and her autonomy restored.
The later legal and financial reviews reinforced the same principle: the most reliable account was the one that separated what actually happened from what fear made plausible. The tracker proved surveillance, the draft financing proved an attempt to create leverage, and the communications proved conflicts, but none of those facts automatically meant the mansion had already been stolen or that every adviser and employee was part of one conspiracy.
That precision protected Morgan twice—first from the scheme itself, and later from allowing the scheme to define every future decision.
The later legal and financial reviews reinforced the same principle: the most reliable account was the one that separated what actually happened from what fear made plausible. The tracker proved surveillance, the draft financing proved an attempt to create leverage, and the communications proved conflicts, but none of those facts automatically meant the mansion had already been stolen or that every adviser and employee was part of one conspiracy.
That precision protected Morgan twice—first from the scheme itself, and later from allowing the scheme to define every future decision.
The later legal and financial reviews reinforced the same principle: the most reliable account was the one that separated what actually happened from what fear made plausible. The tracker proved surveillance, the draft financing proved an attempt to create leverage, and the communications proved conflicts, but none of those facts automatically meant the mansion had already been stolen or that every adviser and employee was part of one conspiracy.
That precision protected Morgan twice—first from the scheme itself, and later from allowing the scheme to define every future decision.
May you like



The later legal and financial reviews reinforced the same principle: the most reliable account was the one that separated what actually happened from what fear made plausible. The tracker proved surveillance, the draft financing proved an attempt to create leverage, and the communications proved conflicts, but none of those facts automatically meant the mansion had already been stolen or that every adviser and employee was part of one conspiracy.
That precision protected Morgan twice—first from the scheme itself, and later from allowing the scheme to define every future decision.