Chapter 2 - THE HOUSE THAT WAS NEVER HIS
Morgan spent the next two days learning how much damage can be attempted without a deed ever changing hands. The Lake Forest mansion belonged to the Hale Family Residence Trust, created by her grandmother Eleanor twelve years before her death. It was worth about $8.6 million and carried no mortgage. Morgan was sole current beneficiary, but the trust—not Morgan personally—held title.
Eleanor’s purpose had been simple. She had watched relatives borrow against inherited properties until nothing remained. She wanted the house protected from impulsive leverage and marital disputes while still allowing Morgan flexibility. Morgan could live there, lease it under restrictions, or sell through the trustee. She could not simply pledge it personally.
There was, however, an exception. If Morgan permanently designated the mansion as her principal marital residence and executed a specific occupancy-and-financing election, the trustee could consider secured borrowing for renovations, tax planning, or family liquidity. Three things were required: Morgan’s written election, independent trustee approval, and a spousal occupancy affidavit. Morgan had done none of them.
Yet her new attorney, Rachel Kim, found a draft package already in existence. It included Morgan’s occupancy election, a spousal affidavit signed by Julian, a proposed trustee-consent form, and a $4.2 million credit facility through Midwest Heritage Private Bank. The borrower was a newly formed entity called Hale Lake Residence Holdings LLC. The manager was Julian Mercer.
Morgan stared at the name. “Hale is my family name.” Rachel nodded. “They used it in the entity name.” Public records showed Julian owned ninety percent of the LLC, while the remaining ten percent was held by a family trust connected to Daniel Voss. The entity had been formed six months earlier.
The proposed loan proceeds were even worse. Approximately $1.1 million would fund renovations and “stabilization,” $900,000 would pay down one of Julian’s business credit lines, $1.3 million would provide working capital to Mercer Urban Ventures, $600,000 would cover professional fees and reserves, and $300,000 would go to a “residence management platform.” That platform was Lakeview Stewardship Partners, a company owned by Daniel Voss’s brother-in-law.
Morgan asked the obvious question. “Why does my estate attorney own part of an LLC trying to borrow against my house?” Rachel answered carefully. “We need to verify whether he directly owns it or whether the interest is held for someone else. Either way, there is an undisclosed conflict.”
The financing had not closed. No mortgage existed. The professional trustee, Great Lakes Trust Company, had not approved anything. Morgan called the trust officer, Andrea Chen, directly. Andrea confirmed that Daniel Voss had contacted the company and said Morgan was considering moving to Lake Forest full time with Julian. The trustee requested Morgan’s direct confirmation before doing anything. None arrived, so the file remained preliminary.
That safeguard mattered. Voss could communicate because he remained attorney of record on some older trust files, but he had no authority to sign for Morgan. The problem was that the system still treated a decades-long lawyer relationship as current enough to begin a process.
Why did Julian need a tracker? Occupancy mattered during underwriting. Repeated overnight stays, package deliveries, utility activity, and smart-home access could support the claim that the mansion was already functioning as Morgan and Julian’s principal residence. Those facts could not replace Morgan’s signature, but they could make the transaction look routine and create pressure: you already live there together, the lender already approved terms, the trustee already reviewed, just formalize what is true.
Morgan thought back over recent months. Julian suddenly preferred weekends at Lake Forest. He insisted they sleep there after dinners. He ordered packages to the mansion. He moved clothes into a guest closet. He complained that the Chicago apartment felt “temporary.” At the time Morgan thought he had fallen in love with the house. Now each act looked like part of a residency dossier.
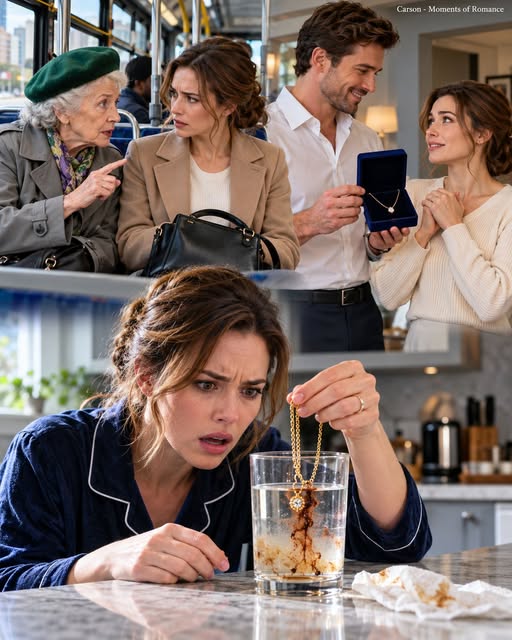
The police cyber unit examined the pendant. It contained a commercial Bluetooth Low Energy beacon with cellular fallback and assisted GPS capability. No microphone. No camera. No audio recorder. It was a location tracker inside custom jewelry.
The black water was not poison or a magical chemical test. Water had entered through a poorly sealed seam. A black conductive coating under the thin gold-plated shell leached into the glass, and the plating separated enough to expose electronics. The accidental soak damaged the unit and triggered the disconnect notification.
The device identifier led to a subscription account registered to Lakeview Stewardship Partners—the same company listed in the financing budget and owned by Voss’s brother-in-law. Suddenly the paper structure and the hardware were connected.
A forensic extraction of Julian’s phone found a folder titled LAKE FOREST — OCCUPANCY SUPPORT. It contained dates, overnight stays, photographs, delivery receipts, smart-lock logs, and notes about Morgan’s visits. At the top was a target: 120 days documented before lender committee.
Morgan felt sick. Romantic weekends had become data points. Dinner deliveries had become proof. Julian had not merely wanted to know where she was. He had been building a factual record around her behavior.
The financing still required Morgan’s consent and trustee approval. The mansion was not already gone. That distinction mattered. The scheme depended on creating momentum and then persuading or pressuring Morgan to sign. The tracker was not a legal key. It was leverage.
And Daniel Voss, the lawyer whose job had been to protect the trust, appeared to be helping design the structure.
May you like



The later legal and financial reviews reinforced the same principle: the most reliable account was the one that separated what actually happened from what fear made plausible. The tracker proved surveillance, the draft financing proved an attempt to create leverage, and the communications proved conflicts, but none of those facts automatically meant the mansion had already been stolen or that every adviser and employee was part of one conspiracy.
That precision protected Morgan twice—first from the scheme itself, and later from allowing the scheme to define every future decision.