Chapter 3 - THE WOMAN ON THE BUS
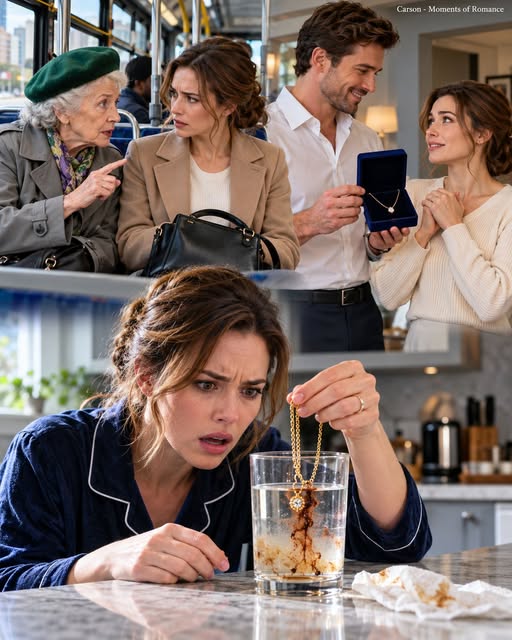
The elderly woman on the bus turned out not to be mysterious at all. Her name was Evelyn Price. She was seventy-four, retired, and had spent twenty-six years in product compliance for an electronics manufacturer. Transit police identified her through the senior-fare card visible in the bus video after Morgan described the warning.
Evelyn agreed to meet. She looked embarrassed when Morgan thanked her. “I thought maybe I was imagining it.” Morgan asked what she had recognized. Evelyn explained that her grandson worked with bicycle security devices and once showed her a compact tracker module. The photograph on Morgan’s phone showed a tiny seam and charging-contact pattern near the edge of the pendant. Evelyn could not know for certain what was inside, so she gave a warning instead of accusing a stranger’s husband of a crime.
“Some gifts aren’t meant to make you beautiful,” Morgan repeated. Evelyn smiled. “It sounded less intrusive than saying, ‘I think your husband is hiding electronics in your jewelry.’” Morgan laughed for the first time in days.
The phone extraction produced the stronger evidence. Julian and Daniel Voss had been discussing the mansion for nine months. Early messages looked legitimate. Julian asked whether the trust could sell or finance the house. Voss explained that Morgan controlled the beneficial decision and that secured borrowing was possible only if she made a principal-residence election and the trustee approved.
Then the conversation changed. Julian wrote: She won’t sign anything tied to my business. Voss answered: Then don’t frame it that way. Residence stabilization first. Business liquidity second. Julian asked whether occupancy history would help. Voss replied that utilities, deliveries, insurance, driver address, and consistent overnight presence could matter in lender diligence but were not substitutes for consent.
Later Julian wrote that Morgan’s phone location was unreliable. Voss replied: Do not do anything illegal. That caveat mattered. Then Daniel separately asked his brother-in-law Craig Mills whether his company’s asset tags could provide passive occupancy logs “if owner consents.” Craig said yes.
Days later Julian commissioned the custom pendant through Craig. Messages showed Craig knew consent was doubtful. Craig asked, Does she know? Julian answered, It’s a gift. Craig replied, That’s not what I asked. Julian said, She’ll be fine. Craig wrote, You’re insane. Julian responded: Just activate.
Craig activated it anyway.
Voss later learned the tracker was concealed. Julian texted: Necklace stopped pinging. Voss replied: Has she found out? That was the message Morgan saw. In isolation it sounded like Voss was directing surveillance. In context, he was asking whether Morgan had discovered the tracker. Still, he knew it existed and did not alert Morgan, the trustee, or the lender.
Worse, Voss had accepted a ten-percent interest in Hale Lake Residence Holdings through his family trust. Julian offered it as compensation for “structuring and long-term advisory support.” Voss therefore had a direct economic interest in a borrowing entity seeking to use Morgan’s trust property as collateral. He should have ceased representing Morgan personally and disclosed the conflict. He did neither.
The messages also showed he tried to keep himself away from the illegal data. When Julian asked how to explain the overnight history, Voss wrote: Use utilities and deliveries. Not device data. Another message: Keep that data out of anything I sign. He was not stopping the surveillance. He was trying to prevent the surveillance from touching documents he authored.
Julian’s plan became clear. Build the occupancy record. Obtain a preliminary term sheet. Make the transaction feel almost finished. Present Morgan with a “residence stabilization” package while her husband’s business deadline approached. Bury business-liquidity uses inside the broader financing and tell her the trust was already prepared to approve.
Would Morgan’s signature still be required? Yes. Could the trustee reject? Yes. Could an independent lawyer kill the deal? Absolutely. That was why Julian feared Rachel Keller. Morgan’s grandmother had once told her, “If anyone pressures you about the house, call Rachel.” Morgan mentioned the name during an argument, and Julian remembered.
The tracker was therefore part of a coercive strategy, not a magic method for stealing title.
Morgan asked Rachel Kim the question she feared most. “Did Julian marry me for the house?” The timeline said no. Morgan and Julian had been married six years. The financing plan began nine months earlier, after Julian’s business started struggling. The marriage had not begun as a con. Something real had deteriorated into exploitation.
That hurt in a different way. Morgan could not dismiss every good memory as fake. Julian had become willing to use the marriage once financial pressure rose. Control behavior intensified with desperation. The mansion became attractive because it was valuable, debt-free, and protected.
The next step was to understand what Julian was trying to save—and why he convinced himself Morgan’s inheritance was available simply because they were married.
The later legal and financial reviews reinforced the same principle: the most reliable account was the one that separated what actually happened from what fear made plausible. The tracker proved surveillance, the draft financing proved an attempt to create leverage, and the communications proved conflicts, but none of those facts automatically meant the mansion had already been stolen or that every adviser and employee was part of one conspiracy.
That precision protected Morgan twice—first from the scheme itself, and later from allowing the scheme to define every future decision.
The later legal and financial reviews reinforced the same principle: the most reliable account was the one that separated what actually happened from what fear made plausible. The tracker proved surveillance, the draft financing proved an attempt to create leverage, and the communications proved conflicts, but none of those facts automatically meant the mansion had already been stolen or that every adviser and employee was part of one conspiracy.
That precision protected Morgan twice—first from the scheme itself, and later from allowing the scheme to define every future decision.
May you like



The later legal and financial reviews reinforced the same principle: the most reliable account was the one that separated what actually happened from what fear made plausible. The tracker proved surveillance, the draft financing proved an attempt to create leverage, and the communications proved conflicts, but none of those facts automatically meant the mansion had already been stolen or that every adviser and employee was part of one conspiracy.
That precision protected Morgan twice—first from the scheme itself, and later from allowing the scheme to define every future decision.