Chapter 2 - THE FIRST ACCOUNT
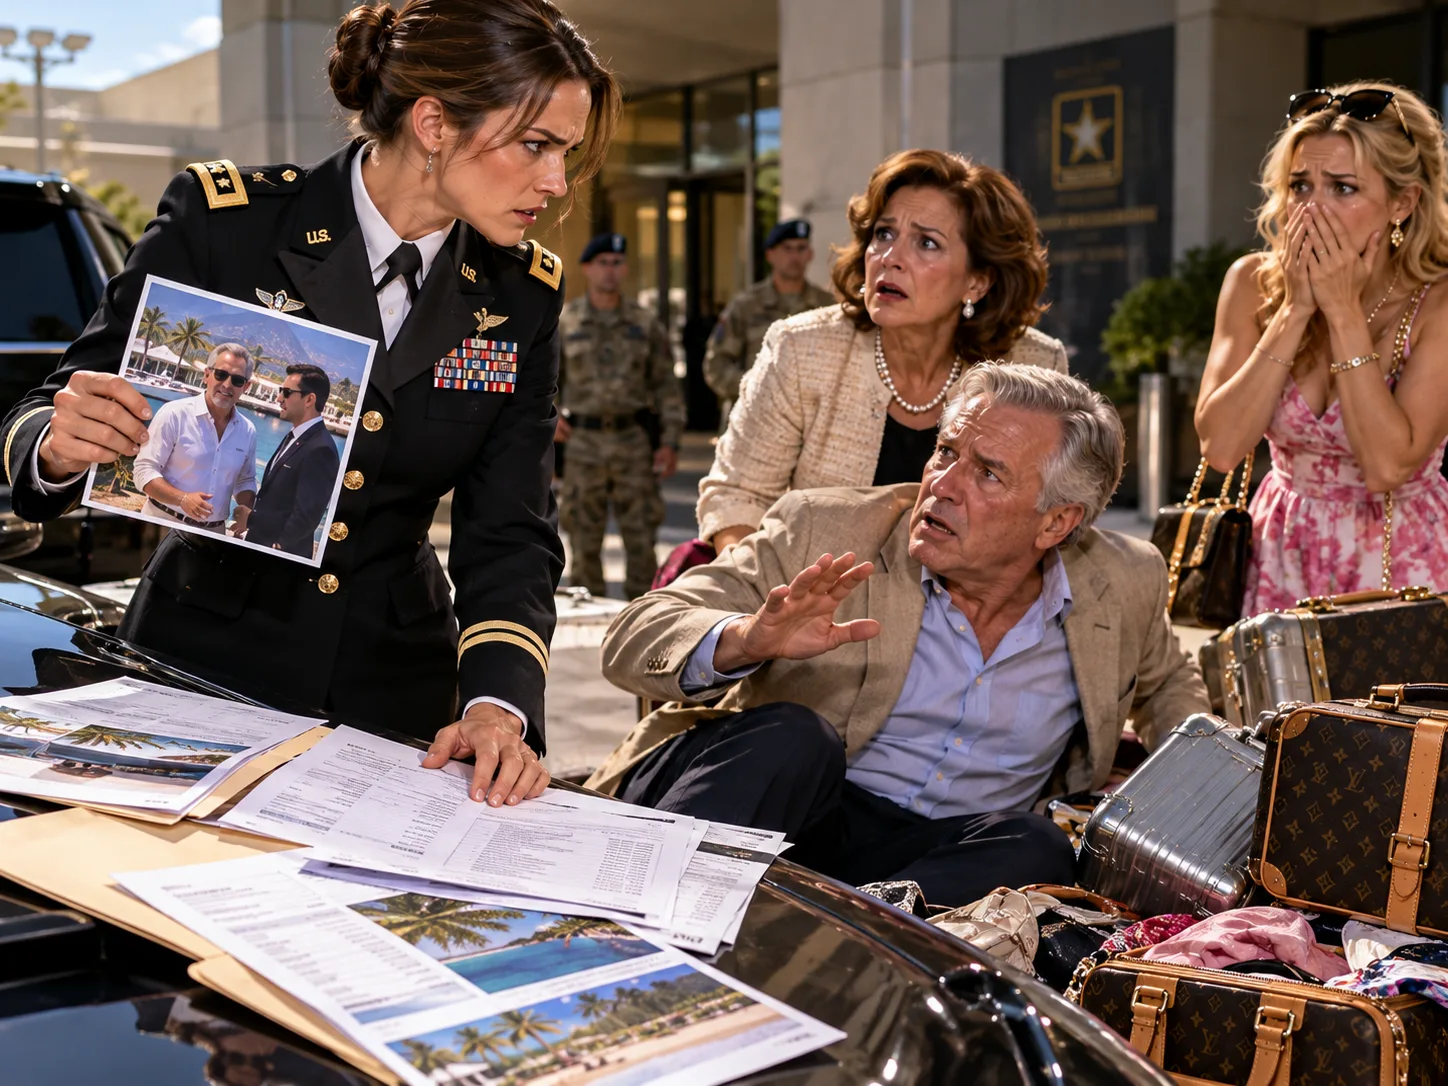
Thomas received a misdemeanor assault summons after the visitor-center cameras confirmed that he had initiated the physical contact, but Rebecca insisted the financial investigation remain separate because she was not going to let one public confrontation replace the slower work of proving identity fraud.
A civilian forensic accountant, Rachel Kim, reconstructed the timeline and discovered that the scheme had not begun with stolen luxury spending at all: six years earlier, a brokerage account had been opened in Rebecca’s name at Sterling Crest Wealth Management with an $11,500 deposit that actually came from Thomas’s own bank account, followed over the next several years by a personal line of credit, an insurance-linked investment account naming Diane as beneficiary, a secured loan using Rebecca’s military salary profile, and later the credit cards that eventually funded the Hawaii trip.
The brokerage file contained a client agreement carrying Rebecca’s signature, a copy of her passport, a photocopy of a military ID, a suitability questionnaire, and a “limited power of attorney” supposedly authorizing Thomas to coordinate while Rebecca served overseas; Rebecca recognized the original power immediately because she really had given Thomas a narrow one-year POA before a deployment so he could handle a vehicle title, a storage contract, and a tax matter, but the version inside Sterling Crest had a five-year expiration and broad investment and borrowing authority she had never granted.
The account used an email address Rebecca had never created and Thomas’s old business phone number, which explained why she had never seen statements.
Then Sterling Crest’s compliance department found the notary record.
The supposed POA extension had been notarized by Susan Graves, Elliot’s sister, five years earlier at a Sterling Crest branch, and her journal said a woman had personally appeared as Rebecca, presented identification, and completed the signing while Thomas and Elliot were present.
Rebecca had been deployed in Germany that day.
Her military travel orders made that impossible.
Susan’s journal also included a strange note: “Father present. Client recovering from facial procedure; identity confirmed by adviser.”
The archived copy of Rebecca’s license showed dark hair, while Susan vaguely remembered the woman appearing in large sunglasses and looking younger.
Madison was blonde and had been in her late twenties.
The possibility hit Rebecca harder than the travel charges because it suggested her younger sister had not merely accepted gifts from fraudulent accounts but may have physically impersonated her before a notary.
The Hawaii photograph acquired a second meaning when Rachel found Sterling Crest’s client-retreat calendar: Elliot Graves had been in Hawaii for a private advisory retreat the same week as Thomas, Diane, and Madison, and the invitation to the retreat had been issued not to Thomas but to “Colonel Rebecca Hale.”
Someone had attended a wealth-management event under Rebecca’s financial identity.
Why now?
Sterling Crest had recently changed its internal identity-verification rules and required legacy accounts operating through old powers of attorney to complete live verification within thirty days; Thomas could not produce Rebecca because she did not know the account existed.
The $184,000 sitting in the brokerage account was therefore frozen while its funding sources were traced, because part came from Thomas and Diane, part from investment growth, and part from credit advances created under Rebecca’s stolen identity.
The Hawaii trip was beginning to look like both a celebration and an emergency exit attempt.
And the question was no longer whether Elliot Graves happened to know her father.
It was whether he had knowingly helped Thomas keep a nonexistent “Rebecca Hale” alive inside the financial system for six years.
The brokerage discovery also explained why Thomas had sometimes asked strange questions about Rebecca’s deployments, mailing address, salary changes, and expected retirement date over the years. At the time she had interpreted those conversations as clumsy parental interest; after the account emerged, investigators could compare each question to later paperwork rather than assuming every family conversation had been sinister.
Some had been ordinary. Some lined up exactly with loan applications. That separation kept the reconstruction credible.
The brokerage discovery also explained why Thomas had sometimes asked strange questions about Rebecca’s deployments, mailing address, salary changes, and expected retirement date over the years. At the time she had interpreted those conversations as clumsy parental interest; after the account emerged, investigators could compare each question to later paperwork rather than assuming every family conversation had been sinister.
Some had been ordinary. Some lined up exactly with loan applications. That separation kept the reconstruction credible.
The brokerage discovery also explained why Thomas had sometimes asked strange questions about Rebecca’s deployments, mailing address, salary changes, and expected retirement date over the years. At the time she had interpreted those conversations as clumsy parental interest; after the account emerged, investigators could compare each question to later paperwork rather than assuming every family conversation had been sinister.
Some had been ordinary. Some lined up exactly with loan applications. That separation kept the reconstruction credible.
The brokerage discovery also explained why Thomas had sometimes asked strange questions about Rebecca’s deployments, mailing address, salary changes, and expected retirement date over the years. At the time she had interpreted those conversations as clumsy parental interest; after the account emerged, investigators could compare each question to later paperwork rather than assuming every family conversation had been sinister.
Some had been ordinary. Some lined up exactly with loan applications. That separation kept the reconstruction credible.
The brokerage discovery also explained why Thomas had sometimes asked strange questions about Rebecca’s deployments, mailing address, salary changes, and expected retirement date over the years. At the time she had interpreted those conversations as clumsy parental interest; after the account emerged, investigators could compare each question to later paperwork rather than assuming every family conversation had been sinister.
Some had been ordinary. Some lined up exactly with loan applications. That separation kept the reconstruction credible.
May you like
The brokerage discovery also explained why Thomas had sometimes asked strange questions about Rebecca’s deployments, mailing address, salary changes, and expected retirement date over the years. At the time she had interpreted those conversations as clumsy parental interest; after the account emerged, investigators could compare each question to later paperwork rather than assuming every family conversation had been sinister.
Some had been ordinary. Some lined up exactly with loan applications. That separation kept the reconstruction credible.