Chapter 6 - The Mortgage Letter Changed The House
A certified mortgage notice arrives as the loan approaches a reset and
the lender requests updated income information. Claire will honor
obligations she legally owes but refuses to keep financing unrelated
household expenses.
An appraisal reveals substantial marital equity. Through counsel Claire
proposes refinance, sale, or a written temporary contribution
arrangement.
Diane calls budgeting cold while Claire calls it the first honest
household plan they have ever read. Diane had spent decades measuring
love by availability.
Anyone who said no looked disloyal to her, which made Claire’s ordinary
financial and personal boundaries feel like betrayal. At this stage that
lesson became harder because every new bill arrived wrapped in an
emotional demand.
Mark had confused access with ownership for years. Shared computers,
supplier accounts, signature scans, spare keys, and Claire’s willingness
to help had taught him that permission was unnecessary whenever he could
call the result a family need.
Claire kept communication factual and saved emotional processing for
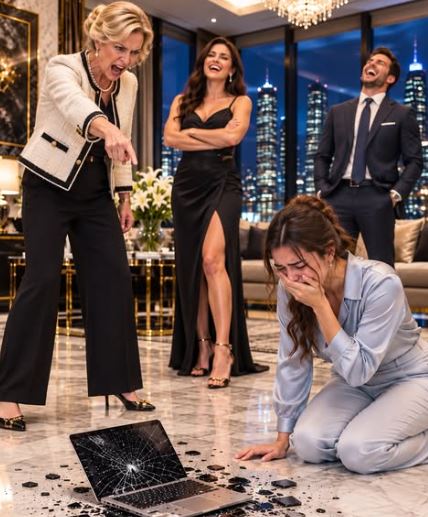
therapy instead of late-night text battles. The shattered laptop became
a timestamp more than an object.
Before 12:17 a.m. Claire explained away the pattern; afterward she asked
who authorized each expense, whose name carried each risk, and who
benefited when nobody asked questions.
Eric started writing obligations down rather than calling Claire
whenever cash became tight, exposing how often she had functioned as the
family emergency system. At work Claire was known for finding weak
assumptions inside complicated financial models.
Separation forced her to apply that discipline to a marriage where love
had allowed assumptions to survive far longer than they ever would in a
spreadsheet. Even ordinary details mattered now, from whose name
appeared on an electric bill to who authorized an automatic transfer
months earlier.
No single cancellation destroyed the household. Panic came from
accumulation: insurance, groceries, taxes, vendor credit, mortgage
support, emergency transfers, bookkeeping, and guarantees had formed an
invisible structure whose strongest beams carried Claire’s name.
The quieter Claire became, the clearer the old pattern looked: urgency
had often prevented her from asking who actually benefited. Claire
refused to celebrate consequences reaching people she once loved.
Relief and grief could occupy the same room, and she wanted a future
built on independence rather than the pleasure of watching somebody else
fail. Nobody received a miraculous transformation, and every repaired
habit had to survive another week before Claire trusted it.
Claire refused to confuse separation with revenge. Rachel reminded her
that lawful boundaries meant protecting her own income, challenging
unauthorized obligations, and ending voluntary support without
sabotaging assets that still had to be divided fairly.
At this stage that lesson became harder because every new bill arrived
wrapped in an emotional demand. Boston moved around the crisis with
indifferent normality: MBTA trains rattled downtown, commuters crossed
Back Bay with coffee, traffic crawled along I-93, and Atlantic wind cut
between glass towers while one suburban household discovered the price
of denial.
Claire kept communication factual and saved emotional processing for
therapy instead of late-night text battles. The phrase family comes
first sounded different once Claire wrote down what it meant in
practice.
Her deadlines, sleep, savings, credit, and career repeatedly came second
while everyone else’s preferences became permanent emergencies. Eric
started writing obligations down rather than calling Claire whenever
cash became tight, exposing how often she had functioned as the family
emergency system.
Documents became more useful than arguments. Mortgage statements, vendor
invoices, tax records, router logs, payroll reports, insurance files,
and messages could not prove every motive, but they stopped the loudest
relative from automatically becoming the most believable.
Even ordinary details mattered now, from whose name appeared on an
electric bill to who authorized an automatic transfer months earlier.
Claire did not experience freedom as constant triumph.
She missed Eric on some mornings, questioned herself on difficult
nights, and learned in therapy that sadness could coexist with certainty
that the old arrangement was no longer acceptable. The quieter Claire
became, the clearer the old pattern looked: urgency had often prevented
her from asking who actually benefited.
Eric’s improvement remained incomplete and intentionally unrewarded. He
could apologize, cooperate, work harder, and confront Mark because those
things were his responsibility, not because they entitled him to another
chance at marriage.
Nobody received a miraculous transformation, and every repaired habit
had to survive another week before Claire trusted it. Diane had spent
decades measuring love by availability.
Anyone who said no looked disloyal to her, which made Claire’s ordinary
financial and personal boundaries feel like betrayal. At this stage that
lesson became harder because every new bill arrived wrapped in an
emotional demand.
Mark had confused access with ownership for years. Shared computers,
supplier accounts, signature scans, spare keys, and Claire’s willingness
to help had taught him that permission was unnecessary whenever he could
call the result a family need.
Claire kept communication factual and saved emotional processing for
therapy instead of late-night text battles. The shattered laptop became
a timestamp more than an object.
Before 12:17 a.m. Claire explained away the pattern; afterward she asked
who authorized each expense, whose name carried each risk, and who
benefited when nobody asked questions.
Eric started writing obligations down rather than calling Claire
whenever cash became tight, exposing how often she had functioned as the
family emergency system. At work Claire was known for finding weak
assumptions inside complicated financial models.
Separation forced her to apply that discipline to a marriage where love
had allowed assumptions to survive far longer than they ever would in a
spreadsheet. Even ordinary details mattered now, from whose name
appeared on an electric bill to who authorized an automatic transfer
months earlier.
No single cancellation destroyed the household. Panic came from
accumulation: insurance, groceries, taxes, vendor credit, mortgage
support, emergency transfers, bookkeeping, and guarantees had formed an
invisible structure whose strongest beams carried Claire’s name.
The quieter Claire became, the clearer the old pattern looked: urgency
had often prevented her from asking who actually benefited. Claire
refused to celebrate consequences reaching people she once loved.
Relief and grief could occupy the same room, and she wanted a future
built on independence rather than the pleasure of watching somebody else
fail. Nobody received a miraculous transformation, and every repaired
habit had to survive another week before Claire trusted it.
Claire refused to confuse separation with revenge. Rachel reminded her
that lawful boundaries meant protecting her own income, challenging
unauthorized obligations, and ending voluntary support without
sabotaging assets that still had to be divided fairly.
At this stage that lesson became harder because every new bill arrived
wrapped in an emotional demand. Boston moved around the crisis with
indifferent normality: MBTA trains rattled downtown, commuters crossed
Back Bay with coffee, traffic crawled along I-93, and Atlantic wind cut
between glass towers while one suburban household discovered the price
of denial.
Claire kept communication factual and saved emotional processing for
May you like
therapy instead of late-night text battles.
================================================================================