Chapter 3 - WHAT THE FOUNDATION RECORDS HID
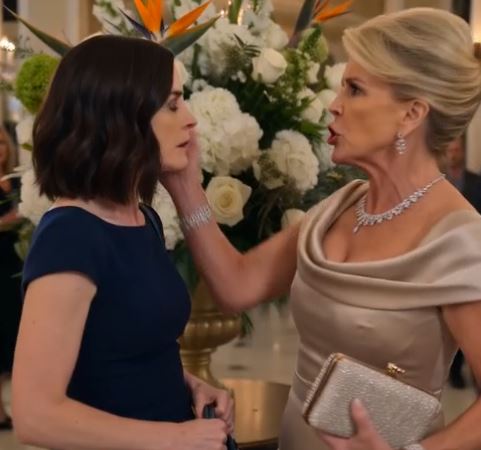
Rebecca Whitmore had not planned to attend the gala until that afternoon. She came because her late mother’s accountant found a foundation letter thanking Eleanor for approving a fund transfer that Rebecca knew her mother could never have signed.
Rebecca handed Emma the original trust instructions Eleanor completed before her death. They specifically prohibited moving the medical fund into event expenses, consulting costs, or general operations.
The forged authorization reversed those restrictions almost word for word. Whoever created it had access to Eleanor’s old signature and enough knowledge of the foundation’s internal language to make the document look routine.
Emma asked Rebecca whether Eleanor had worked closely with Victoria. Rebecca said Victoria frequently visited during the final year of Eleanor’s life and often brought documents for donor recognition programs.
That access provided opportunity but not proof. Emma refused to turn suspicion into conclusion without records.
The foundation’s technology consultant examined the forged file metadata. It had been created on a laptop assigned to the gala committee office and modified under Victoria’s administrative login.
Victoria’s attorney argued that staff shared the computer. The consultant agreed, then produced badge-access records showing Victoria was the only authorized person in the office during the creation window.
Charles’s consulting company received the first payment two days later. The timing tightened the connection.
Auditors expanded their review beyond the current year. They found donor restrictions repeatedly changed through scanned letters, digital approvals, and internal memoranda.
Some changes were legitimate. Others contained formatting anomalies, duplicate signature images, or dates that did not match donor correspondence.
Emma felt the scope widen beneath her. She had expected sloppy accounting when she accepted the director position, not a system designed to turn charitable restrictions into private revenue.
Jonathan admitted the board had relied too heavily on Victoria because she was effective at fundraising. She brought wealthy people into rooms, secured sponsorships, and made every gala look successful.
Success had become camouflage. As long as headline donation totals rose, too few people asked how much money actually reached the programs.
Emma ordered a grant-by-grant reconciliation. Every promised dollar would be matched against bank transfers, beneficiary receipts, vendor contracts, and donor restrictions.
The first result was devastating. A housing program listed as receiving $500,000 had actually received $290,000.
A youth scholarship partner was short $115,000. An emergency medical fund showed administrative expenses nearly four times higher than comparable programs.
The missing money did not all flow to the Langfords. Some went through layers of vendors, which meant additional people might have participated knowingly or unknowingly.
Emma told the board not to assume every vendor was corrupt. The investigation needed to distinguish fraud from legitimate services, poor controls, and vendors who had been misled.
That careful approach earned Rebecca’s trust. She agreed to provide her mother’s full records and serve as a witness if necessary.
Late that night, auditors found something stranger than forged donor approvals. The foundation maintained two versions of its annual grant ledger, and only one had ever been shown to the full board.
While auditors rebuilt the records, the investigation moved carefully because a convincing story was not the same thing as a proven transaction. Emma insisted that every conclusion identify the document, bank record, witness, or digital trail supporting it.
While auditors rebuilt the records, that discipline frustrated people who wanted immediate answers, but it protected the foundation from replacing one kind of misconduct with reckless accusation. Emma would rather wait a day for verification than ruin an innocent person with a convenient assumption.
While auditors rebuilt the records, outside counsel also separated criminal questions from governance failures. Some decisions might be unethical without being crimes, while other transactions could violate law even if they had been disguised as ordinary administration.
While auditors rebuilt the records, every meeting ended with an evidence list and an uncertainty list. Emma found the second list just as important because institutions became dangerous when leaders stopped admitting what they did not yet know.
While auditors rebuilt the records, the board preserved emails, accounting exports, badge records, contracts, and archived backups. Staff were told not to delete even embarrassing material because embarrassment was no longer a valid records policy.
While auditors rebuilt the records, at home, Emma discovered that composure in public did not prevent delayed emotion in private. She could lead an audit all afternoon and still feel her body tense when a stranger raised a voice behind her.
While auditors rebuilt the records, she spoke with a counselor rather than pretending the assault was irrelevant beside the financial case. Physical humiliation and professional betrayal were different injuries, and neither needed to compete for importance.
While auditors rebuilt the records, her friends learned not to turn the incident into a heroic story every time they introduced her. Emma wanted space to be competent without constantly being described as the woman who survived a country-club scandal.
While auditors rebuilt the records, small routines helped more than dramatic reassurance. Coffee before work, evening walks, ordinary grocery shopping, and weekends without foundation documents reminded her that the investigation was part of life rather than all of it.
While auditors rebuilt the records, emma also became more attentive to how easily people judged one another by clothing, speech, education, or confidence. She could not eliminate bias from every room, but she could refuse to build foundation procedures around it.
While auditors rebuilt the records, the reforms were intentionally unglamorous. Approval matrices, conflict disclosures, vendor checks, independent reconciliations, and documented exceptions would never fill a ballroom, but they could keep money from disappearing after the applause ended.
While auditors rebuilt the records, emma required staff to understand why each control existed. A rule followed blindly could become theater, while a rule connected to a known risk was more likely to survive pressure from powerful people.
While auditors rebuilt the records, board members received training on restricted gifts and related-party transactions. Several admitted they had previously treated those subjects as matters for accountants rather than responsibilities of governance.
While auditors rebuilt the records, the foundation also reduced dependence on a handful of wealthy personalities. Fundraising relationships remained valuable, but no donor, chair, or gala organizer would become indispensable enough to operate beyond scrutiny.
While auditors rebuilt the records, transparency did not mean publishing private beneficiary information. Emma drew a firm line between financial accountability and exposing vulnerable people for public reassurance.
May you like
While auditors rebuilt the records, the investigation moved carefully because a convincing story was not the same thing as a proven transaction. Emma insisted that every conclusion identify the document, bank record, witness, or digital trail supporting it.
While auditors rebuilt the records, that discipline frustrated people who wanted immediate answers, but it protected the foundation from replacing one kind of misconduct with reckless accusation. Emma would rather wait a day for verification than ruin an innocent person with a convenient assumption.