Chapter 5 - WHAT ELEANOR BUILT
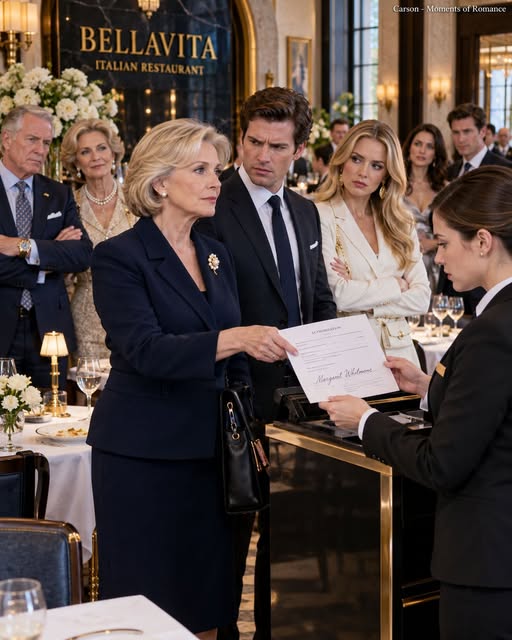
Whitmore Hospitality Group began with one failing inn outside Boston.
Eleanor’s late husband, Thomas, bought a minority interest as an investment.
When he died unexpectedly at fifty-two, the inn was losing money.
The easy choice would have been sale.
Eleanor was forty-three.
Richard was seventeen.
She took over.
Not because she dreamed of hospitality.
Because selling would have crystallized debt and threatened Thomas’s estate.
She learned.
Payroll.
Food cost.
Labor law.
Renovation.
Liquor licensing.
Revenue management.
She fired one corrupt purchasing manager.
Hired a chef who stayed twenty years.
Refinanced.
Turned the inn profitable.
Then acquired Belladonna with two partners.
Bought them out later.
Expanded.
By sixty-eight, Whitmore Hospitality Group was privately valued around $186 million.
Eleanor personally controlled fifty-eight percent.
The twenty-eight-percent block Richard attempted to pledge had an estimated value of roughly $52 million, though private-company valuations fluctuate.
The proposed $42 million loan therefore used most of that block’s value as collateral.
If RMW defaulted, Eleanor could lose a huge portion of her control.
That was why she never casually pledged shares.
Richard told investigators:
“She would have gotten them back once I refinanced.”
That sentence stunned Rachel Kim.
Collateral is not borrowed jewelry.
Risk is real.
Richard believed confidence could replace permission.
Eleanor’s late husband had once made a similar mistake on a smaller scale.
Before death, Thomas pledged a family investment without telling her because he was sure a deal would work.
It did work eventually.
But Eleanor learned about pledge only after bank notice.
She forgave Thomas.
Then changed every company governance rule:
no personal guarantees without written board approval;
no family signatures by assumption;
no undisclosed collateral.
Richard had grown up around those rules but never understood why.
Irony.
Belladonna’s staff knew Eleanor as owner because she visited monthly.
She reviewed menus, employee retention, and budgets.
Richard had not been to Belladonna with her in years.
He chose the restaurant because one of his friends bragged it was “impossible to book.”
Vanessa’s assistant secured table through concierge service.
Neither knew ownership.
The reveal was coincidence.
But not impossible coincidence.
Eleanor owned several high-end properties around Boston.
Richard simply paid no attention.
That hurt her more than surprise pleased her.
He did not know what she built because he never asked.
He knew what she could pay.
Independent board members at Whitmore Hospitality learned of forgery Monday morning.
They moved quickly.
Richard had never been officer or director.
No corporate access to remove.
They placed a fraud alert on shares.
Notified transfer agent.
Notified banks.
Required live video confirmation for any future pledge or sale over $1 million.
No hidden stock moved.
No company crisis.
This was Eleanor’s business, not a house of cards.
The sixth chapter would follow Vanessa.
Her role went beyond impersonating Eleanor before a notary.
But the evidence would also show she had not conceived the plan.
She joined after Richard’s business had already deteriorated, partly because her own lifestyle depended on RMW surviving.
Money and marriage had fused.
Independent valuation was intentionally conservative. Private hospitality shares do not have one magic price, and lenders apply discounts to illiquid collateral. The $52 million estimate for the proposed block therefore remained a range, not a guaranteed cash value.
That nuance kept the financial stakes large without turning paper wealth into fantasy.
Independent valuation was intentionally conservative. Private hospitality shares do not have one magic price, and lenders apply discounts to illiquid collateral. The $52 million estimate for the proposed block therefore remained a range, not a guaranteed cash value.
That nuance kept the financial stakes large without turning paper wealth into fantasy.
Independent valuation was intentionally conservative. Private hospitality shares do not have one magic price, and lenders apply discounts to illiquid collateral. The $52 million estimate for the proposed block therefore remained a range, not a guaranteed cash value.
That nuance kept the financial stakes large without turning paper wealth into fantasy.
Independent valuation was intentionally conservative. Private hospitality shares do not have one magic price, and lenders apply discounts to illiquid collateral. The $52 million estimate for the proposed block therefore remained a range, not a guaranteed cash value.
That nuance kept the financial stakes large without turning paper wealth into fantasy.
Independent valuation was intentionally conservative. Private hospitality shares do not have one magic price, and lenders apply discounts to illiquid collateral. The $52 million estimate for the proposed block therefore remained a range, not a guaranteed cash value.
That nuance kept the financial stakes large without turning paper wealth into fantasy.
Independent valuation was intentionally conservative. Private hospitality shares do not have one magic price, and lenders apply discounts to illiquid collateral. The $52 million estimate for the proposed block therefore remained a range, not a guaranteed cash value.
That nuance kept the financial stakes large without turning paper wealth into fantasy.
Independent valuation was intentionally conservative. Private hospitality shares do not have one magic price, and lenders apply discounts to illiquid collateral. The $52 million estimate for the proposed block therefore remained a range, not a guaranteed cash value.
That nuance kept the financial stakes large without turning paper wealth into fantasy.
Independent valuation was intentionally conservative. Private hospitality shares do not have one magic price, and lenders apply discounts to illiquid collateral. The $52 million estimate for the proposed block therefore remained a range, not a guaranteed cash value.
That nuance kept the financial stakes large without turning paper wealth into fantasy.
Independent valuation was intentionally conservative. Private hospitality shares do not have one magic price, and lenders apply discounts to illiquid collateral. The $52 million estimate for the proposed block therefore remained a range, not a guaranteed cash value.
That nuance kept the financial stakes large without turning paper wealth into fantasy.
May you like
Independent valuation was intentionally conservative. Private hospitality shares do not have one magic price, and lenders apply discounts to illiquid collateral. The $52 million estimate for the proposed block therefore remained a range, not a guaranteed cash value.
That nuance kept the financial stakes large without turning paper wealth into fantasy.