Chapter 8 - The Lottery Ticket Had Its Own Problem
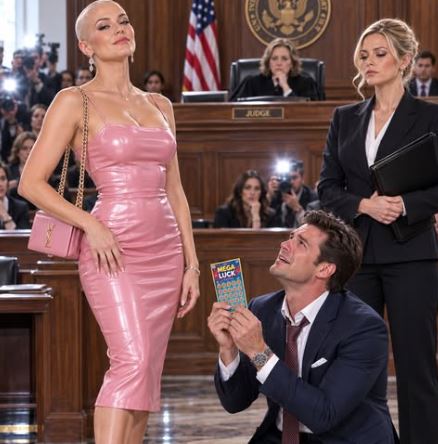
Doug had known more than he admitted. Doug learns that state law and the
timing of the ticket purchase may affect how some proceeds are
characterized in divorce. Rachel does not overclaim; instead, both sides
trace exactly when the ticket was bought, with which funds, and when the
prize became legally payable.
Doug had spent years complaining about grocery prices, utility bills,
and restaurant tips, which made his transformation after the jackpot
feel less like new personality than permission for an old insecurity to
become loud. The discovery of opened mail transformed Doug from merely
foolish into someone who had quietly tested the value of his marriage
before announcing his exit.
“Can I stop the divorce?” Doug whispered after the figures were read.
Rachel treated the divorce like litigation rather than theater,
organizing bank statements, tax returns, entity documents, valuation
reports, and dates before allowing emotion anywhere near strategy.
Rachel’s discipline kept the story from becoming a fantasy about hiding
wealth, because separate property still had to be disclosed even when it
was not divisible. “Can I stop the divorce?” Doug whispered after the
figures were read.
Evie began separating two questions she had once confused: whether Doug
regretted hurting her and whether Doug regretted discovering that
leaving her had not made him the richer spouse. Trevor’s involvement
widened the story beyond divorce, connecting one husband’s insecurity to
people who saw a private company as an opportunity.
“You are asking that question after learning her income,” his lawyer
said. “Think carefully about what that sounds like.” Bennett Industrial
Holdings had grown from Evie’s grandfather’s Midwestern machine shop
into a private network of industrial real estate, specialty
manufacturing, logistics facilities, and long-term partnerships.
The Bennett fortune carried responsibility with it: employees, tenants,
lenders, minority partners, pension obligations, environmental reviews,
and communities depending on long-term decisions. “You are asking that
question after learning her income,” his lawyer said. “Think carefully
about what that sounds like.”
Evie’s city had taught her that wealth rarely announced itself with
sports cars; sometimes it sat quietly in county deeds, audited
partnerships, warehouse leases, and distributions deposited on schedule.
Evie did not need Doug destroyed; she needed the legal and corporate
boundaries around her life restored.
“I do not want his lottery ticket,” Evie said. “I want an honest
resolution and my life back.” Every disclosure carried context:
acquisition date, source of funds, title, tax basis, ownership
percentage, and whether later marital contributions created any
legitimate claim that needed careful analysis.
Evie’s father had taught her that a balance sheet could be enormous
while a person’s daily life remained ordinary. “I do not want his
lottery ticket,” Evie said. “I want an honest resolution and my life
back.”
Rachel treated the divorce like litigation rather than theater,
organizing bank statements, tax returns, entity documents, valuation
reports, and dates before allowing emotion anywhere near strategy. By
the final hearing, the most important number was not $1.5 million,
$820,000, or Bennett’s valuation—it was the number of times Doug had
chosen money over honesty when he thought nobody could see.
“You photographed my mail before you became rich,” Evie told Doug. “So
this was never just Saturday-morning arrogance.” Rachel repeatedly
warned Evie not to treat Doug’s arrogance as legal stupidity; even an
unsympathetic spouse retained rights, and accuracy would protect Evie
better than revenge.
Doug’s attempt to reverse course became painful because Evie could
remember the man who once called her his anchor, even while recognizing
why he wanted that anchor again. “You photographed my mail before you
became rich,” Evie told Doug. “So this was never just Saturday-morning
arrogance.”
Doug’s sudden luxury spending created the appearance of abundance, but
taxes, withholding, professional fees, and impulsive purchases made his
headline jackpot very different from permanent wealth. Evie found the
courtroom irony satisfying, but satisfaction was not the same as a legal
theory, and she refused to build her future on humiliation.
“Trevor told me Bennett was collapsing,” Doug admitted. “I believed him
because I wanted to.” Evie began separating two questions she had once
confused: whether Doug regretted hurting her and whether Doug regretted
discovering that leaving her had not made him the richer spouse.
The discovery of opened mail transformed Doug from merely foolish into
someone who had quietly tested the value of his marriage before
announcing his exit. “Trevor told me Bennett was collapsing,” Doug
admitted. “I believed him because I wanted to.”
Bennett Industrial Holdings had grown from Evie’s grandfather’s
Midwestern machine shop into a private network of industrial real
estate, specialty manufacturing, logistics facilities, and long-term
partnerships. Doug’s jackpot mattered less with every chapter of the
financial review; the real issue was what his behavior revealed once he
believed the balance of power had changed.
“Money did not end this marriage,” Evie said. “It revealed what you
thought marriage was worth when you believed you no longer needed me.”
Rachel treated the divorce like litigation rather than theater,
organizing bank statements, tax returns, entity documents, valuation
reports, and dates before allowing emotion anywhere near strategy.
Trevor’s involvement widened the story beyond divorce, connecting one
husband’s insecurity to people who saw a private company as an
opportunity. “Money did not end this marriage,” Evie said. “It revealed
what you thought marriage was worth when you believed you no longer
needed me.”
Evie had never hidden her identity from Doug; she had simply refused to
turn family wealth into the center of their marriage, living on a
comfortable budget and reinvesting most distributions. Rachel’s
discipline kept the story from becoming a fantasy about hiding wealth,
because separate property still had to be disclosed even when it was not
divisible.
“He asked for full disclosure,” Rachel said. “So we give him full,
accurate disclosure.” Bennett Industrial Holdings had grown from Evie’s
grandfather’s Midwestern machine shop into a private network of
industrial real estate, specialty manufacturing, logistics facilities,
and long-term partnerships.
Evie did not need Doug destroyed; she needed the legal and corporate
boundaries around her life restored. “He asked for full disclosure,”
Rachel said. “So we give him full, accurate disclosure.”
Every disclosure carried context: acquisition date, source of funds,
title, tax basis, ownership percentage, and whether later marital
contributions created any legitimate claim that needed careful analysis.
The Bennett fortune carried responsibility with it: employees, tenants,
lenders, minority partners, pension obligations, environmental reviews,
and communities depending on long-term decisions.
“I thought Bennett was debt and old warehouses,” Doug said. “You never
lived like this.” Every disclosure carried context: acquisition date,
source of funds, title, tax basis, ownership percentage, and whether
later marital contributions created any legitimate claim that needed
careful analysis.
By the final hearing, the most important number was not $1.5 million,
$820,000, or Bennett’s valuation—it was the number of times Doug had
chosen money over honesty when he thought nobody could see. “I thought
Bennett was debt and old warehouses,” Doug said. “You never lived like
this.”
Evie closed the day with a truth Doug’s lottery ticket had accidentally
May you like
exposed: money had never been the secret center of their marriage;
character was, and character had finally entered the record.