Chapter 2 - THE LOAN DANIEL NEVER TOOK
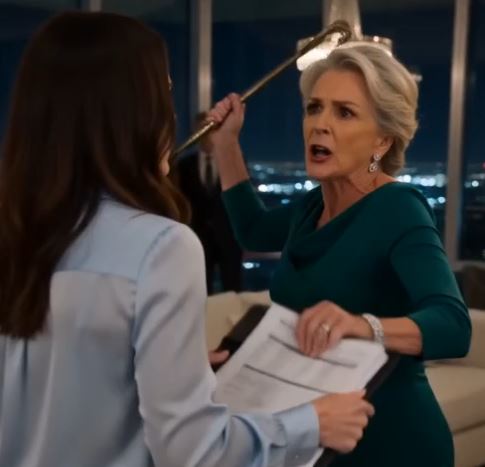
The police did not make immediate arrests for the financial allegations. They documented the assault, photographed Claire’s injuries, collected statements, preserved the recording, and advised Daniel to secure every bank and business account connected to the disputed transactions. Margaret left the penthouse under formal restriction related to the assault complaint. Ethan left separately. By midnight, the broken ornaments had been swept into a box, but the bank statements remained on the dining table in neat rows like an accusation nobody could clean away.
Daniel stood at the windows looking over Chicago. He had spent most of his adult life being the dependable Hale—the son who took over Hale Logistics when his father William died, the brother everyone called in emergencies, the man Margaret described as “strong enough to handle anything.” Now strength felt like the very trait his family had used against him. Claire sat nearby and told him they did not need to understand everything before morning. Daniel answered that his mother had just admitted using his authorization for a $1.8 million loan he never requested.
At eight the next morning, Daniel and Claire sat with attorney Maya Brooks, a specialist in fraud and fiduciary disputes. Maya listened to the recording without interruption, then asked whether Margaret ever had power of attorney. Daniel said yes—years earlier, during William’s illness, Daniel had signed a limited authority so Margaret could pay certain personal bills while he traveled. It had strict transaction limits and expired after William died. Maya asked for a copy.
The lender, Meridian Capital, produced its file within hours after Daniel formally disputed the obligation. The borrower was Hale Property Ventures LLC, an entity tied to Ethan’s mixed-use development. The guarantor was Daniel Hale. The collateral was listed as a minority ownership interest in a warehouse outside Joliet. Daniel stared at the documents and said he had never guaranteed the loan, never pledged the warehouse, and never authorized his mother to do either.
The guaranty package contained a notarized power of attorney that looked almost identical to Daniel’s old one. Almost. The expiration date had been changed. The transaction limit had disappeared. The signature looked like Daniel’s. The notary was Laura Kent, a longtime Hale family friend who had worked around their businesses for fifteen years. Claire knew her from holidays. Daniel knew her from childhood. The fraud suddenly looked less like one desperate decision and more like a structure involving people who already understood how the family worked.
Then Daniel noticed the collateral description. The Joliet warehouse had once been his personally, but three years earlier he transferred it into an employee profit-sharing structure. Drivers, warehouse staff, mechanics, and long-term employees held beneficial interests. Daniel still appeared in legal title records through a trust arrangement, but he could not lawfully pledge the property for a private family loan without trustee approval.
Maya immediately brought in corporate counsel and the independent trustee. No approval existed. If Meridian had enforced the guarantee, dozens of employees could have faced litigation over property connected to their retirement interests. Claire watched Daniel’s anger change. When the crime affected only his money, he looked betrayed. When he understood employees had been exposed, he looked ashamed, even though he had not created the risk.
Meridian’s old correspondence revealed another layer. The lender had sent a default notice nine months earlier. It went to Margaret, Ethan, and an address supposedly belonging to Daniel. Daniel had never seen it. The address was the office of Margaret’s private accountant. A response letter carried Daniel’s signature and promised that he accepted full responsibility for the financing. Daniel had not written it.
The chief financial officer of Hale Logistics arrived with another file. Before William died, he had created a family trust holding controlling shares of the company. Daniel knew the trust existed but believed his succession was largely settled. It was not. He controlled operations as chief executive, but permanent ownership would transfer only after a review period. One clause allowed trustees to suspend or reduce a beneficiary’s interest if that beneficiary intentionally pledged protected assets or engaged in unauthorized financial misconduct.
Claire looked at the forged loan. “So if someone made it look like Daniel pledged that warehouse improperly…”
Maya finished the thought. “They could create a basis to challenge his trust distribution.”
Daniel’s face changed. Ethan was also a beneficiary, though secondary. If Daniel’s interest were reduced, Ethan’s position could improve.
The missing withdrawals were now only one piece of a larger question. Had Margaret forged Daniel’s authority only to rescue Ethan’s failing project, or had someone later realized the fraud could also change who inherited a family fortune?
The recording played again in Claire’s mind: If Daniel finds the old loan file, all of us are finished.
Not Ethan.
Not Margaret.
All of us.
And Daniel finally understood that his mother’s violence had not begun because Claire accused her of taking money. It began because Claire found the thread holding together a lie powerful enough to rewrite the future of the entire Hale family.
Maya warned them that fraud inside families often survived because formal systems assumed familiarity reduced risk. Banks saw a mother carrying an old power of attorney. Lenders saw a brother presenting a family-backed project. Accountants saw names they recognized. Every institution had a reason not to ask one more question. The lesson was not that families could never be trusted; it was that trust without verification created opportunities nobody intended to create. Daniel began to understand that good controls were not insults to love. They were protections for love when fear or urgency distorted judgment.
Maya warned them that fraud inside families often survived because formal systems assumed familiarity reduced risk. Banks saw a mother carrying an old power of attorney. Lenders saw a brother presenting a family-backed project. Accountants saw names they recognized. Every institution had a reason not to ask one more question. The lesson was not that families could never be trusted; it was that trust without verification created opportunities nobody intended to create. Daniel began to understand that good controls were not insults to love. They were protections for love when fear or urgency distorted judgment.
May you like
Maya warned them that fraud inside families often survived because formal systems assumed familiarity reduced risk. Banks saw a mother carrying an old power of attorney. Lenders saw a brother presenting a family-backed project. Accountants saw names they recognized. Every institution had a reason not to ask one more question. The lesson was not that families could never be trusted; it was that trust without verification created opportunities nobody intended to create. Daniel began to understand that good controls were not insults to love. They were protections for love when fear or urgency distorted judgment.
Maya warned them that fraud inside families often survived because formal systems assumed familiarity reduced risk. Banks saw a mother carrying an old power of attorney. Lenders saw a brother presenting a family-backed project. Accountants saw names they recognized. Every institution had a reason not to ask one more question. The lesson was not that families could never be trusted; it was that trust without verification created opportunities nobody intended to create. Daniel began to understand that good controls were not insults to love. They were protections for love when fear or urgency distorted judgment.