Chapter 2 - THE CRUISE MARGARET NEVER TOOK
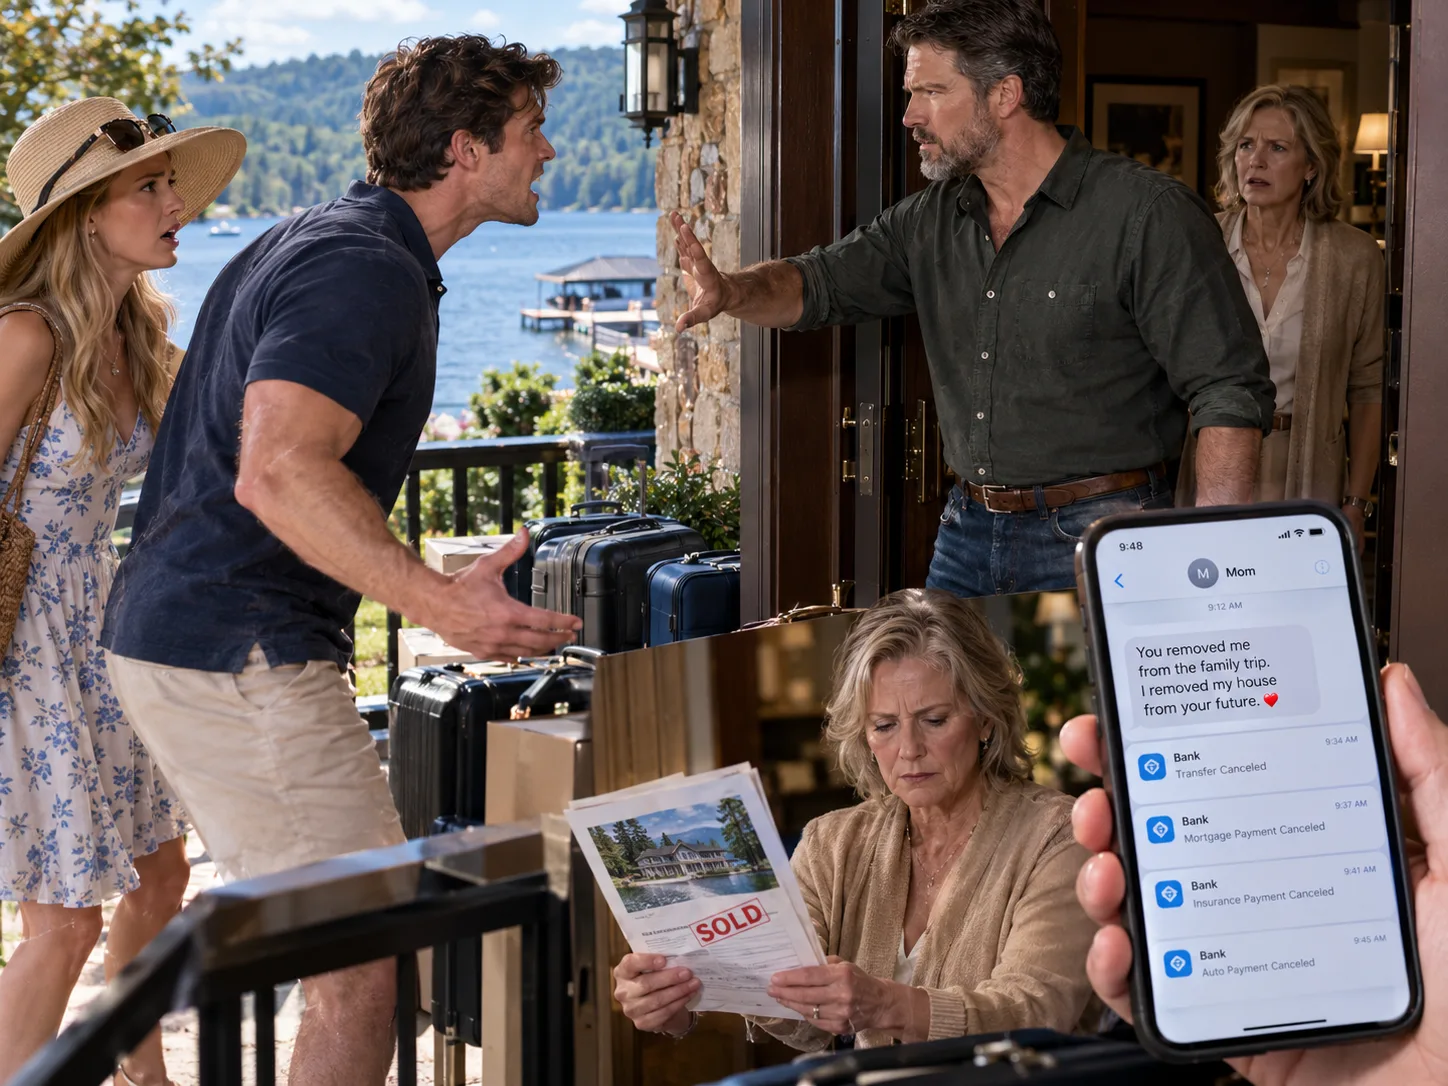
Three weeks earlier, Margaret Whitmore had been looking forward to the cruise.
At sixty-eight, widowed for nine years, she had spent most holidays organizing other people’s schedules and paying more than anyone admitted.
The cruise was supposed to be her first family trip where she did not plan meals, book rooms, or host everyone.
Nathan proposed it.
Seven nights in the Caribbean.
Three balcony suites.
Private shore excursion.
Holiday package.
He told her:
“You deserve this.”
Margaret believed him.
She paid the initial deposit.
Not all of it.
Enough.
Nathan and Claire were supposed to reimburse part.
Julia paid her own portion.
Margaret’s reservation was confirmed.
Then, four days before departure, Margaret received an automated email:
YOUR RESERVATION HAS BEEN CANCELED.
She called the cruise line.
The agent said:
“Your travel coordinator requested cancellation.”
“My what?”
“The primary contact on the family booking.”
Nathan.
Margaret called him.
He answered after three attempts.
“Mom, don’t make a thing out of this.”
“Why is my cabin canceled?”
Silence.
Then:
“Claire and I thought the trip would be easier if it was just us and Julia.”
Margaret sat down.
“You invited me.”
“I know.”
“I paid the deposit.”
“We’ll sort that out.”
“Why didn’t you tell me?”
“Because you get emotional.”
That sentence changed her.
Not loudly.
Quietly.
For years Margaret had covered shortfalls because Nathan always had a reason.
Bad mortgage timing.
Unexpected tax bill.
Claire between jobs.
Rental vacancy.
Car repair.
School tuition for one of Claire’s nieces they were helping.
Temporary.
Margaret’s help had become infrastructure.
Nathan stopped treating it as generosity.
He planned around it.
Claire did too.
When Margaret asked whether they still expected her to pay the remaining cruise balance, Nathan hesitated.
“Well, the final payment already processed.”
From Margaret’s card.
She looked at the amount.
$12,840.
Her canceled cabin refund had been converted partly into future cruise credit attached to the primary booking account.
Nathan still expected the trip to proceed using her money.
Margaret said:
“No.”
Nathan:
“Mom.”
“No.”
“You already paid.”
“I can dispute charges I did not authorize after my cancellation.”
“Don’t embarrass us.”
That phrase.
Embarrass us.
Margaret hung up.
She did not argue again.
The next morning she called her attorney, Sarah Vale.
Then her accountant, Peter Dawson.
Then her bank.
The first thing Sarah told her was:
“Do not make irreversible decisions because you’re angry about a cruise.”
Margaret agreed.
“I’m angry about ten years.”
That answer changed the meeting.
They reviewed.
Lake house:
solely Margaret’s name.
Atlanta support transfers:
voluntary monthly gifts.
Insurance payments:
voluntary.
Family supplemental card:
Margaret primary holder.
Rental-condo property-tax payments:
voluntary gifts.
No contract requiring continuation.
Then Sarah asked:
“What do you actually want?”
Margaret said:
“I want to stop financing adults who treat my help like a debt I owe them.”
Good.
Not:
destroy son.
The financial review began.
Peter Dawson listed every recurring payment Margaret made for Nathan and Claire.
The total shocked even Margaret.
Over the prior three years:
mortgage support: $126,000.
vehicle/insurance: $31,400.
rental-condo taxes: $22,700.
travel and family-card expenses: $48,000.
miscellaneous transfers and reimbursements: more than $60,000.
Nearly three hundred thousand dollars.
Not illegal.
Gifts.
Margaret had chosen.
But seeing the total changed her sense of scale.
Then Peter found something she had not chosen.
A brokerage account at Whitmore Securities showed three transfers to an investment platform called Harlow Ridge Ventures.
$40,000.
$55,000.
$35,000.
Margaret did not recognize them.
“Could these be something I approved?”
Peter checked memos.
FAMILY INVESTMENT ALLOCATION.
Margaret frowned.
She had no memory.
That alone proved nothing.
Sarah asked bank for device logs.
One transfer originated from Margaret’s home laptop.
Possible.
The other two from an IP address linked to Nathan and Claire’s Atlanta home.
Now serious.
Margaret called neither of them.
Instead she changed passwords, froze external transfers, and requested fraud review.
Then she looked at the lake house.
Lake Briarwood had been bought with her late husband David in 1998.
Nathan loved it as a child.
After David died, Margaret kept it because Nathan said:
“Dad would want us to.”
Nathan and Claire began spending summers there.
At first welcomed.
Then they started leaving clothes.
Furniture.
Kayaks.
A wine fridge.
They referred to “our lake place.”
Nathan changed a bedroom without asking.
Claire hired landscapers and sent Margaret the bill.
Margaret tolerated.
Every time she suggested selling, Nathan said:
“You can’t sell Dad’s legacy.”
But Nathan did not pay property taxes.
Insurance.
Major repairs.
Dock replacement.
Roof.
Margaret did.
Sarah asked:
“Do you want to sell because he canceled a cruise?”
Margaret answered:
“I’ve wanted to sell for four years. The cruise only made me stop asking permission.”
That distinction mattered.
They ordered appraisal.
The lake house market was strong.
A buyer already interested through neighbor referral:
Thomas Greene, a retired civil engineer who had rented on the lake for years.
Margaret did not list publicly first because Thomas made a clean offer near appraisal value, no financing contingency beyond proof of funds, flexible closing.
She had independent broker confirm fairness.
She accepted.
Not a fire sale.
Not revenge price.
Legal closing.
Before closing, Margaret had professional movers inventory Nathan and Claire’s belongings.
Sarah reviewed occupancy.
Nathan and Claire had no lease.
No ownership.
No established exclusive tenancy; they used rooms as invited family guests and maintained primary residence in Atlanta.
Still, counsel advised written notice.
Margaret emailed and mailed notice while they were at sea:
personal belongings removed and stored,
permission to occupy revoked,
house under contract,
do not attempt entry after closing.
Cruise internet showed message delivered.
Nathan later claimed he never read.
That did not undo sale.
Margaret also stopped recurring gifts.
She did not cancel Nathan’s own insurance policies improperly.
She stopped paying them.
Difference.
She did not seize his accounts.
She stopped transfers from hers.
The estate plan came next.
Sarah asked again:
“Anger?”
Margaret said:
“Clarity.”
Her existing will left lake house specifically to Nathan, a cash amount to Julia, and residue split equally.
But lake house would be gone.
Specific gift would lapse under ordinary rules depending plan.
Margaret did more thoughtfully.
She replaced the old will with a revocable living trust.
Why?
Privacy.
Continuity.
Incapacity planning.
Clear management.
She did not completely disinherit Nathan.
Not yet.
Instead, she removed assumptions.
Her estate would be divided:
a protected trust for Julia,
a discretionary trust for Nathan with independent trustee and no control over principal,
charitable gifts,
education trusts for grandchildren if any.
Nathan would not receive property outright automatically.
Why discretionary trust?
Because Margaret had realized he treated future inheritance as present borrowing capacity.
She wanted his eventual benefit separated from control.
Then came beneficiary designations.
Life insurance.
Retirement accounts.
Some previously listed Nathan and Julia equally.
Margaret updated after counsel explained which assets passed outside will.
Not to punish.
To align.
No beneficiary would receive a sudden amount without structure.
Finally, the brokerage fraud review.
Harlow Ridge Ventures.
Who owned it?
Corporate records showed the managing member was Claire Whitmore.
Margaret stared.
Her daughter-in-law.
The lake house sale was already underway.
But now the family conflict had changed from entitlement to possible unauthorized transfers.
May you like
And while Nathan was on the cruise believing his mother sat home wounded and waiting for an apology, Margaret spent nine days doing something far more consequential.
She stopped treating assumptions as agreements.