Chapter 2 - THE GUARANTEE EMMA NEVER SIGNED
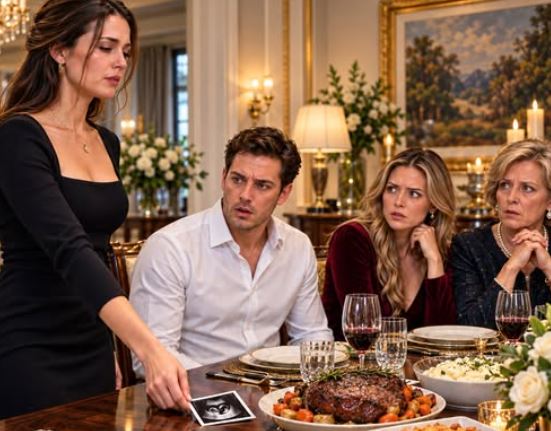
The guarantee packet arrived the next morning.
Naomi Park brought it to Robert’s office in a sealed digital-print binder.
Emma sat on the couch with a bottle of water and the ultrasound photograph tucked inside her bag.
She had not slept.
Ryan had left the house after police took brief statements about the dinner altercation.
Robert had also given a statement.
He admitted punching Ryan.
He did not excuse it.
The family conflict would be handled separately from the financial review.
Naomi appreciated that.
She opened the binder.
The first pages looked ordinary.
Loan application.
Borrower financials.
Collateral schedule.
Personal guarantees from Ryan.
Corporate guarantee from Northline Wellness Holdings.
Then the page with Emma’s name.
LIMITED GUARANTOR CONSENT.
Emma Hale Mercer Trust.
The signature looked perfect.
Too perfect.
Emma stared.
“I know that signature.”
Naomi asked what she meant.
“It’s mine.”
Robert looked confused.
Emma shook her head.
“Not from this.”
She had signed a trust distribution authorization two years earlier after purchasing a small apartment.
The signature included a distinctive long stroke beneath the final letters.
She remembered because the digital tablet skipped and she signed twice.
Naomi asked the trustee for the old file.
It arrived within an hour.
Side by side, the signatures appeared identical.
Caleb Wong, a forensic document examiner, would later confirm the digital image had been reused.
Same pixel pattern.
Same skip.
Same compression artifacts.
The guarantee did not contain a fresh signature.
It contained a copy.
Emma felt cold.
Naomi moved to the execution certificate.
Electronic witness:
Madison Mercer.
Emma looked at Robert.
Ryan’s sister had witnessed Emma signing a document Emma never signed.
That explained Madison’s face at dinner.
Her shove no longer looked like random hostility.
It looked like panic attached to knowledge.
The bank’s file included a video-verification waiver.
Why waived?
Medical scheduling conflict.
Emma laughed.
“What medical conflict?”
The form said Emma had been receiving fertility treatment and requested reduced meeting burden.
Emma’s anger became sharper.
She was pregnant.
She had never authorized anyone to use her medical life as an excuse for avoiding identity verification.
The bank officer who processed the package, Julia Feld, had initialed a note:
Direct owner call requested before funding.
That sentence mattered.
The loan had not fully funded.
Only a preliminary $1.5 million bridge draw had been released against Ryan’s company receivables, not Emma’s trust collateral.
The larger guarantee remained pending direct verification.
Emma exhaled.
No lien had attached to her trust.
No principal had moved.
Again, an attempted overreach caught before completion.
Naomi emphasized that.
Emma needed facts, not imagined catastrophe.
Then they examined where the copied signature came from.
Ryan’s company files contained an old scanned trust document because Emma once provided it for a mortgage application on their marital home.
Ryan had access.
Madison had access through Northline’s shared diligence folder.
The bank had access only after submission.
The source could be traced further.
Why did Northline need the guarantee?
Madison’s wellness company had expanded quickly.
Boutique clinics.
Corporate memberships.
High-end supplements.
Real revenue.
Real costs.
Northline owed $3.1 million on equipment leases and had a large supplier obligation due.
Ryan’s company owed even more.
The proposed facility bundled the businesses under one cross-supported arrangement.
Ryan had offered personal guarantees.
Not enough.
Madison’s company lacked collateral.
The trust guarantee made the combined package stronger.
Naomi asked Emma whether she ever discussed supporting Madison’s company.
“No.”
Ever supporting Ryan’s company?
“Not with my trust.”
Ever telling Ryan he could use trust income?
“Yes.”
Income was different.
Emma sometimes transferred quarterly distributions into their joint account.
Ryan may have begun treating the trust as family liquidity.
Legally and emotionally, those were different things.
Emma understood that now.
Naomi contacted Victor Alvarez, the independent trustee.
Victor was furious.
He had not approved the guarantee.
The trust instrument required trustee consent before principal could secure third-party debt.
The packet falsely stated:
Trustee acknowledgment pending administrative completion.
Victor had never acknowledged anything.
The document therefore had two missing approvals.
Emma.
Trustee.
Yet Ryan proceeded far enough to obtain conditional credit.
Why?
Because he expected the missing steps would eventually be filled.
That pattern emerged quickly.
Ryan’s attorney sent a letter claiming Emma had verbally agreed to “support the family businesses if needed.”
Emma remembered the conversation.
It happened eighteen months earlier.
Ryan complained about financing costs.
Emma said:
“If things ever got really bad, we’d figure it out together.”
He now treated that sentence as broad consent.
Naomi shook her head.
Figuring it out together is not a $7.2 million guarantee.
Emma almost smiled.
Then the bank provided another page.
Internal deal note:
R. Mercer says divorce documentation may simplify separation of guarantor exposure if transaction closes before filing.
Emma read it twice.
There it was.
Divorce.
The word appeared in the loan process before Ryan screamed it at dinner.
Robert leaned back.
“He planned the timing.”
Naomi corrected gently.
“He discussed divorce timing in relation to the loan. We do not yet know why.”
Emma looked at the page.
Ryan wanted the divorce filed after the guarantee process moved but before Emma discovered how her trust had been used.
Maybe he believed a separation agreement could later ratify or allocate the risk.
Maybe he wanted to isolate financial exposure.
Maybe something else.
The guarantee explained the fear.
It did not yet explain the whole plan.
Emma closed the binder.
Her hand moved to her abdomen.
Nine weeks pregnant.
A marriage breaking.
A signature copied.
A sister-in-law listed as witness.
The dinner had not started the crisis.
It had interrupted it.
Ryan’s business problems were real rather than invented. His development company had overexpanded into two luxury projects at the same time, and falling presales created a cash crisis that made bad decisions feel urgent without making those decisions lawful.
May you like
Madison’s company existed and sold real products. The issue was not that everything around her was fake; the issue was that she and Ryan had used family relationships to solve financing problems without giving Emma the information required for meaningful consent.
Emma’s trust had been created by her late mother, not Robert. That detail mattered because Ryan often described Emma’s separate assets as “family money,” language that blurred the legal distinction between property Emma owned and resources he believed marriage made available to everyone.