Chapter 2 - THE ASHFORD HOUSE
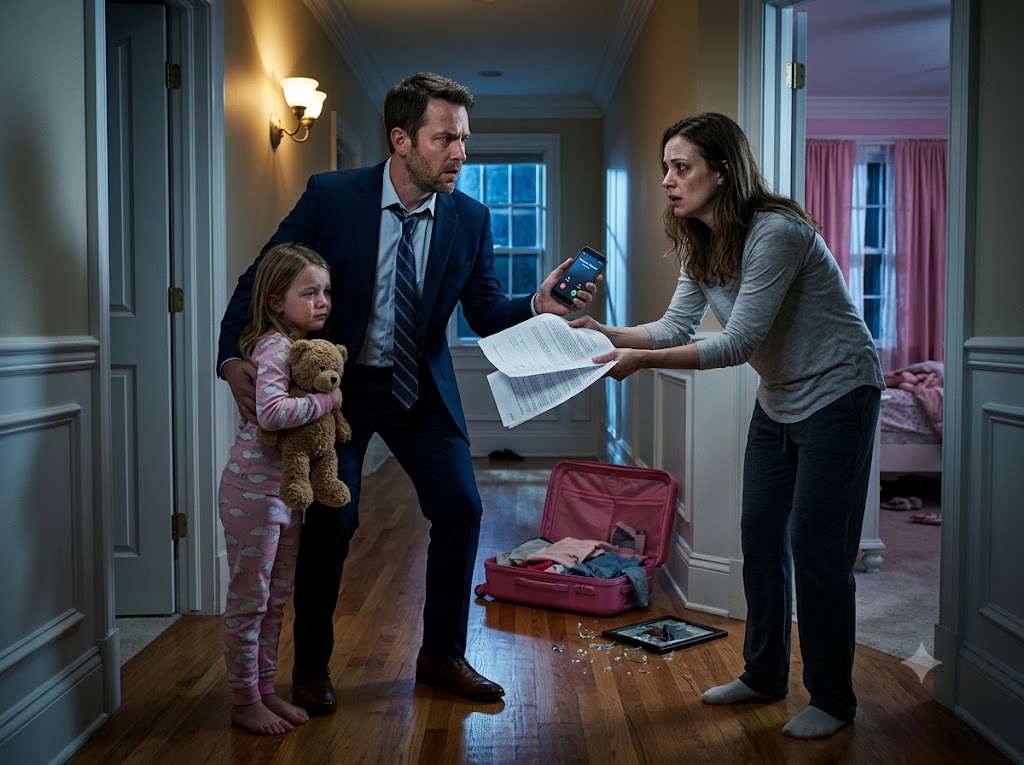
Daniel did not sleep.
Sophie slept beside him in the guest room with the teddy bear recovered from the bedroom floor, one hand wrapped around Daniel’s sleeve as though even sleep required proof he had not disappeared.
Lauren stayed downstairs with her own attorney on speakerphone.
Rachel Kim advised Daniel not to interrogate her.
Not yet.
The documents had to be preserved.
The phone call had to be confirmed.
The address had to be checked.
By 7:30 the next morning, Rachel had pulled the county property record.
The Ashford house had not been sold.
It was owned by Bennett Family Residential Trust.
Trustee:
Melissa Bennett Cross.
Beneficiary:
Sophie Bennett.
Daniel stared.
“What?”
Rachel turned the laptop toward him.
The house his father supposedly sold two years earlier had been transferred into a trust for Daniel’s daughter three months before Thomas Bennett died.
Daniel had never seen this deed.
“Why didn’t I know?”
Rachel did not speculate.
She pulled Thomas’s probate file.
The will Daniel received after his father’s death left the bulk of Thomas’s assets equally between Daniel and Melissa.
The Ashford house was listed as “previously disposed of.”
That phrase now looked false.
A separate trust transfer existed outside probate.
Someone had withheld it.
Who prepared the trust?
A small estate firm called Hawthorne & Pike.
The attorney who drafted it, Martin Pike, was retired but alive.
Rachel called.
He agreed to speak after verifying Daniel’s identity.
Martin remembered.
Thomas created the trust because he was worried about a family conflict involving Sophie.
“What conflict?” Daniel asked.
Martin hesitated.
“I need to review the file before discussing details.”
Fair.
By noon, he sent a secure copy of Thomas Bennett’s trust letter.
Daniel read.
To my granddaughter Sophie,
The Ashford property is yours because this house belonged to your grandmother’s family before it came to me. I do not want it used to settle debts, business disputes, or arguments between my children.
Daniel looked at Rachel.
“Debts?”
Rachel kept reading.
Thomas had discovered six months before his death that Melissa borrowed against several estate-adjacent assets through a private lender after her husband’s medical business collapsed.
Melissa had personal debt.
Large.
Thomas refused to let Ashford secure it.
He moved the house into Sophie’s trust.
Why Sophie?
Because Daniel had stable income and Melissa had no children.
Thomas wanted one property removed from sibling conflict and preserved for the next generation.
He appointed Melissa trustee initially because she lived closer and managed the property.
That looked contradictory now.
Rachel frowned.
“Why make the indebted child trustee?”
The letter answered partly.
Thomas believed Melissa’s financial trouble temporary.
He trusted her more than the lender.
Bad judgment perhaps.
Then another clause.
At Sophie’s age seven, if Daniel and Lauren remained married and Sophie resided primarily with them, beneficial control stayed protected.
If Sophie’s primary residence changed under court-approved guardianship to Melissa, trustee could petition to use trust income for maintenance of Ashford and Sophie’s support.
Still no right for Melissa to take ownership.
But practical control over trust distributions increased.
Daniel understood.
“If Sophie lived with Melissa, Melissa could ask the trust to pay expenses at the house.”
“Yes.”
“Could she pay her own debts?”
“No. Not legally.”
“But she could live in the house with Sophie and have housing costs covered.”
“Potentially, if a court and successor trustee allowed.”
Successor trustee?
Rachel found.
At Thomas’s death, Melissa served only until independent co-trustee appointed at Sophie’s seventh birthday.
That birthday was in four days.
There.
A clock.
On Sophie’s seventh birthday, Hawthorne Fiduciary Services would join as co-trustee and require full accounting.
Melissa had four days before independent review.
Daniel felt cold.
The midnight pickup was not arbitrary.
If Sophie began residing at Ashford before the co-trustee took over, Melissa could claim an established caregiving arrangement and seek expanded maintenance distributions.
Still subject to scrutiny.
But stronger than after the fiduciary arrived.
Why involve Lauren?
Rachel asked.
“What financial pressure does your wife have?”
Daniel did not know.
Their household looked comfortable.
He ran an engineering-consulting firm.
Lauren managed a boutique interior-design business.
Separate business accounts under prenup.
He assumed she was doing well.
Rachel said.
“Assumption is not a financial statement.”
They requested voluntary disclosure through Lauren’s attorney.
Lauren refused initially.
Then a bank alert arrived on Daniel’s phone.
Joint emergency savings account.
A $75,000 outgoing transfer had been attempted overnight.
Blocked because Daniel’s secondary approval was missing.
Recipient:
Cross Residential Services LLC.
Melissa’s company.
Daniel stared.
That created direct link.
Lauren had tried to send money to Melissa.
Why?
She finally agreed to limited meeting with both attorneys.
Sophie was with Daniel’s longtime friend Hannah Reed and a child counselor from the family court intake team.
No adult conversation around her.
Lauren sat across from Daniel.
Red eyes.
No sleep.
Daniel did not yell.
“Why was Sophie being sent to Ashford?”
Lauren looked at her hands.
“Because Melissa said she could fix everything.”
“What everything?”
“My business.”
There.
Lauren’s design firm, Lark House Interiors, had lost two major clients.
She used credit lines to cover payroll.
Then more debt.
Current obligations:
$310,000.
Not catastrophic for a successful family perhaps.
But Lauren had also signed a personal guarantee with Harbor Crest Lending at high interest.
Another $180,000.
Total near $490,000.
Daniel had no idea.
“You hid half a million dollars?”
“I thought I could fix it.”
“With our daughter?”
Lauren flinched.
“No.”
“Then explain.”
Melissa offered Lauren $200,000 from Cross Residential Services if Sophie temporarily relocated to Ashford for six months.
Not “purchase.”
A consulting advance tied to Lauren helping renovate and stage the property for a charitable residential program.
That was the cover.
The real condition was Sophie’s residence.
Why?
Melissa wanted to establish legitimate trust-funded occupancy before co-trustee review.
Then use maintenance contracts through her own company to receive payments.
Could that siphon money?
Potentially if inflated.
Illegal if fraudulent.
Lauren claimed Melissa said everything would be authorized.
“Did you believe her?”
“At first.”
“And later?”
Silence.
“Lauren.”
“I knew Daniel would say no.”
So she forged.
How?
She scanned his signature from a school authorization.
Simple.
No stranger hacker.
Her laptop would confirm.
Then the most painful question.
“Why throw Sophie out of her room at midnight?”
Lauren cried.
“Melissa said pickup people needed to see she was already separated from the household.”
Daniel stared.
“Separated?”
“The placement service wanted confirmation there was no last-minute conflict.”
“So you made one.”
Lauren covered her face.
“I thought if I made it look final, I wouldn’t back out.”
There.
She was forcing herself.
Not Sophie.
Herself.
She packed suitcase earlier.
Hid documents under mattress because she panicked when Daniel came home early.
Sophie saw.
Then moved it.
The caller from midnight was not a kidnapper.
It was James Porter, a licensed family-placement coordinator hired by Melissa’s attorney to facilitate what he believed was a voluntary kinship placement.
He had copies bearing Daniel’s forged consent.
Once Daniel disputed, James suspended everything and contacted child services.
Another professional process stopped.
Good.
The unknown address belonged to Sophie.
The person waiting there was Melissa.
But the most dangerous part remained.
Why was Melissa desperate enough to risk forged guardianship and trust manipulation four days before an independent fiduciary review?
Rachel pulled county lien records.
Cross Residential Services had a judgment lien.
$1.1 million.
Melissa’s debt was much larger than Thomas knew.
And Ashford was the only valuable property she had been managing that creditors could not touch because it belonged to Sophie’s trust.
She could not take the house.
But if she controlled its maintenance contracts, renovations, and household expenses through Sophie’s placement, she could create a stream of trust payments to her own companies.
The plan was not to make Sophie disappear forever.
It was to turn a seven-year-old into the justification for cash flow.
Daniel looked at Lauren.
“You were going to send our daughter away so your business could survive and Melissa could bill her trust.”
Lauren whispered.
“I told myself it was temporary.”
“How temporary?”
“Six months.”
Sophie had heard “leaving.”
No child translates six months of secret relocation as temporary.
Daniel stood.
The marriage did not end in that room.
Not legally.
But trust did.
Rachel then received another email.
From Martin Pike.
He had found an unsigned draft Thomas left with his file.
One paragraph was underlined.
If Melissa ever attempts to use Sophie’s residence to access trust funds for her own benefit, remove her immediately as trustee and audit all prior payments.
Thomas had anticipated the risk.
The independent fiduciary arriving in four days was not routine.
It was a safeguard activated because Thomas never fully trusted Melissa’s financial judgment.
Melissa knew.
That was why midnight mattered.
Lauren had become the bridge.
May you like
The suitcase was not packed because a mother suddenly hated her child.
It was packed because two adults had convinced themselves a little girl’s home could be moved temporarily to solve financial problems that belonged to them.